Best CD Rates in Bismarck, ND: Top Local Picks
When you want to secure a guaranteed return on your cash without risking market downturns, certificates of deposit (CDs) remain one of the most reliable vehicles available. If you are shopping for the strongest cd rates bismarck nd has to offer, local depositors have access to a healthy mix of homegrown community banks, regional institutions, and member-owned credit unions. Understanding how these local yields stack up—and how to structure your deposits—can significantly increase your annual interest earnings.
Understanding the CD Market in Bismarck
Certificates of deposit require you to lock away a set amount of cash for an agreed-upon term, ranging from a few months to several years. In exchange for surrendering immediate liquidity, the issuing bank or credit union provides a fixed annual percentage yield (APY) that typically outpaces standard checking and basic savings accounts.
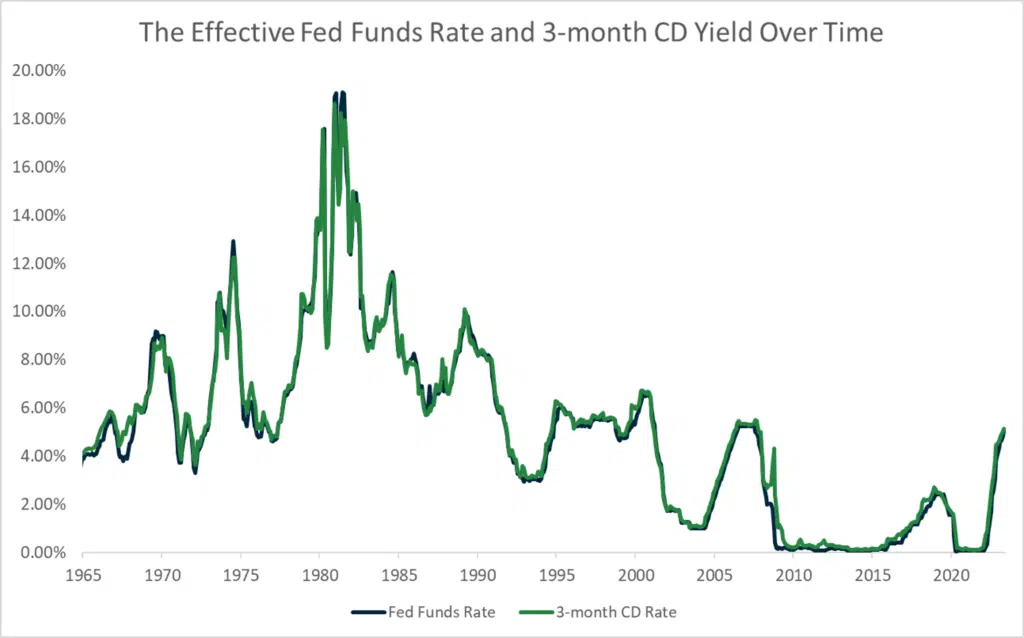
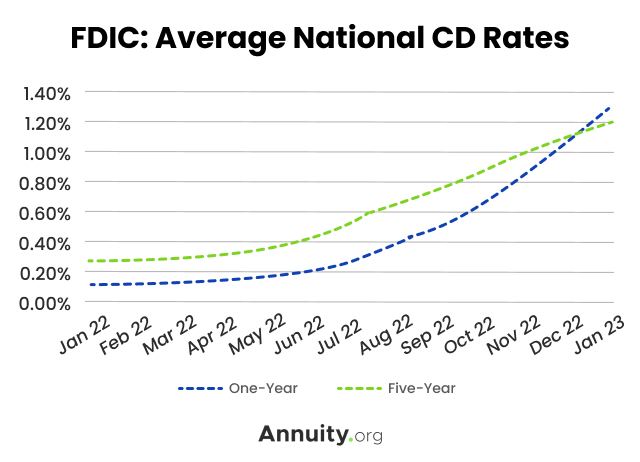
In recent years, the interest rate environment has created unique opportunities for savers in North Dakota. An inverted or flat yield curve has frequently pushed short-term CD yields higher than long-term alternatives. Consequently, terms between 6 and 14 months have offered some of the highest APYs available in the Burleigh County market.
Where to Find Competitive CD Rates in Bismarck, ND
Depositors in the Bismarck-Mandan metropolitan area are fortunate to have an active, community-focused banking sector. While national online banks offer convenient digital setups, local institutions often match or beat those yields through promotional "special" certificates designed to attract regional capital.
1. Local Credit Unions
Credit unions are member-owned, not-for-profit cooperatives, which often allows them to return profits to members in the form of higher dividend rates on share certificates (the credit union term for CDs). In Bismarck, notable options include:
- Capital Credit Union: Headquartered locally, Capital Credit Union frequently runs special certificate promotions for terms like 7, 11, or 17 months. Membership is widely accessible to anyone living or working in the region.
- Railway Credit Union: Serving Mandan, Bismarck, and surrounding areas, Railway often provides competitive short-term yields with low minimum deposit barriers.
2. Independent & Community Banks
Community banks are deeply tied to North Dakota’s agricultural and commercial economies. To fund local lending, they frequently offer compelling CD promotions:
- Gate City Bank: Well known for its widespread branch presence across Bismarck (including locations on State Street and Century Avenue), Gate City Bank regularly features promotional relationship CDs with consumer-friendly features.
- Starion Bank: With deep local roots in the Bismarck-Mandan area, Starion often structures unique tiered-rate CDs where higher balances unlock top-tier APYs.
- BNC National Bank: Operating full-service locations in Bismarck, BNC combines regional community banking with robust personal savings and certificate products.
- Dakota Community Bank & Trust: A staple in central and western North Dakota, this bank frequently provides competitive traditional CD terms with fixed, predictable returns.
3. Online Banks vs. Bismarck Brick-and-Mortar
While local branches provide in-person relationships, you should always compare local offerings against top national online banks. Online-only institutions avoid the overhead costs of physical locations and sometimes offer slightly higher yields on standard terms (like 2-year through 5-year CDs). However, Bismarck institutions frequently run "odd-month" promotional specials (such as a 9-month or 15-month CD) that surpass national averages.
Comparing CD Terms: Short-Term vs. Long-Term
Selecting the right maturity length involves balancing your income goals against your expected need for liquidity.

Short-Term CDs (3 to 12 Months)
Short-term CDs are ideal when you have funds set aside for near-term milestones, such as a home down payment, property taxes, or home renovations. In an environment where the Federal Reserve maintains elevated baseline rates, short-term CDs often provide the highest annual percentage yields available.
Medium-to-Long-Term CDs (18 Months to 5 Years)
While longer-term yields may look slightly lower during periods of economic uncertainty, locking in a multi-year certificate protects you against rate drops. If benchmark interest rates decrease over the next several years, a 36- or 60-month CD locked in today continues earning at that initial rate until maturity.
How to Maximize Your Return with a CD Ladder
Rather than committing all your savings into a single maturity date, consider setting up a CD ladder. This time-tested strategy smooths out interest rate fluctuations while ensuring you get periodic access to portions of your cash.
Sample Bismarck CD Ladder Strategy
Assume you have $20,000 you want to keep protected and earning interest:
- Deposit $5,000 into a 6-month CD.
- Deposit $5,000 into a 12-month CD.
- Deposit $5,000 into an 18-month CD.
- Deposit $5,000 into a 24-month CD.
Every six months, one of your certificates matures. When it does, you can either take the money if you need it, or roll it into a new 24-month CD at the prevailing rate. Over time, your entire balance earns the higher yields typical of longer terms, yet a quarter of your total funds becomes liquid every half-year.
Key Details to Check Before You Open a CD
A headline rate is important, but reading the fine print ensures that fees or limitations do not erode your earnings.
- Early Withdrawal Penalties: If you must pull your principal out before the term ends, banks will charge a penalty—typically anywhere from 90 to 365 days of earned interest. Ensure you have a separate emergency fund in an accessible checking or savings account before locking money away.
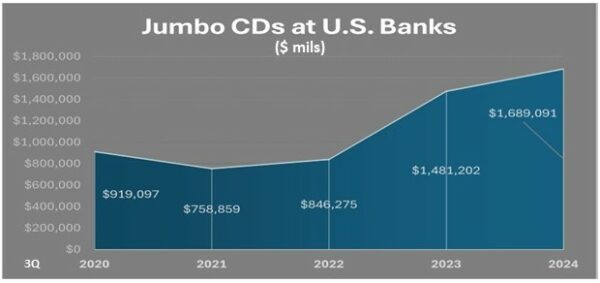
- Minimum Balance Requirements: Some institutions require as little as $500, while others reserve their highest APYs for balances of $10,000, $25,000, or more (often designated as "Jumbo CDs").
- Compounding Frequency: Daily compounding yields slightly more over time than monthly or quarterly compounding. Always look at the APY rather than the simple interest rate, as APY accounts for compounding.
- Deposit Insurance: Verify that your financial institution is insured. Look for the FDIC logo at banks or the NCUA logo at credit unions. Both protect your aggregate deposits up to at least $250,000 per depositor, per insured institution, for each account ownership category.
Getting the Most from Your Bismarck Savings
Securing the best fixed return on your money comes down to active comparison. Check the rate sheets published weekly by Bismarck’s credit unions and local community banks, watch for seasonal specials, and weigh those options against online rates. By matching your maturity timelines to your personal financial plans, you can build a stable, fully insured cash reserve that works quietly and effectively in your favor.