Can You Get a Car Loan with a 597 Credit Score?
Finding yourself with a credit score of 597 can feel stressful, especially if you desperately need reliable transportation for work or family. Sitting firmly in the subprime credit category, a 597 score means traditional lenders will view you as a higher-risk borrower. However, the automotive financing market is vastly different from the mortgage or personal loan markets. Cars are secured assets, meaning lenders can repossess the vehicle if you default, which makes them more willing to take a chance on drivers with lower scores.

Securing a 597 credit score car loan is entirely possible, but it requires preparation, realism, and a strategy to avoid predatory lending traps. Here is a complete guide on what to expect, how interest rates work at this tier, and actionable steps you can take to drive off the lot with a manageable monthly payment.
Understanding Your Position with a 597 Credit Score
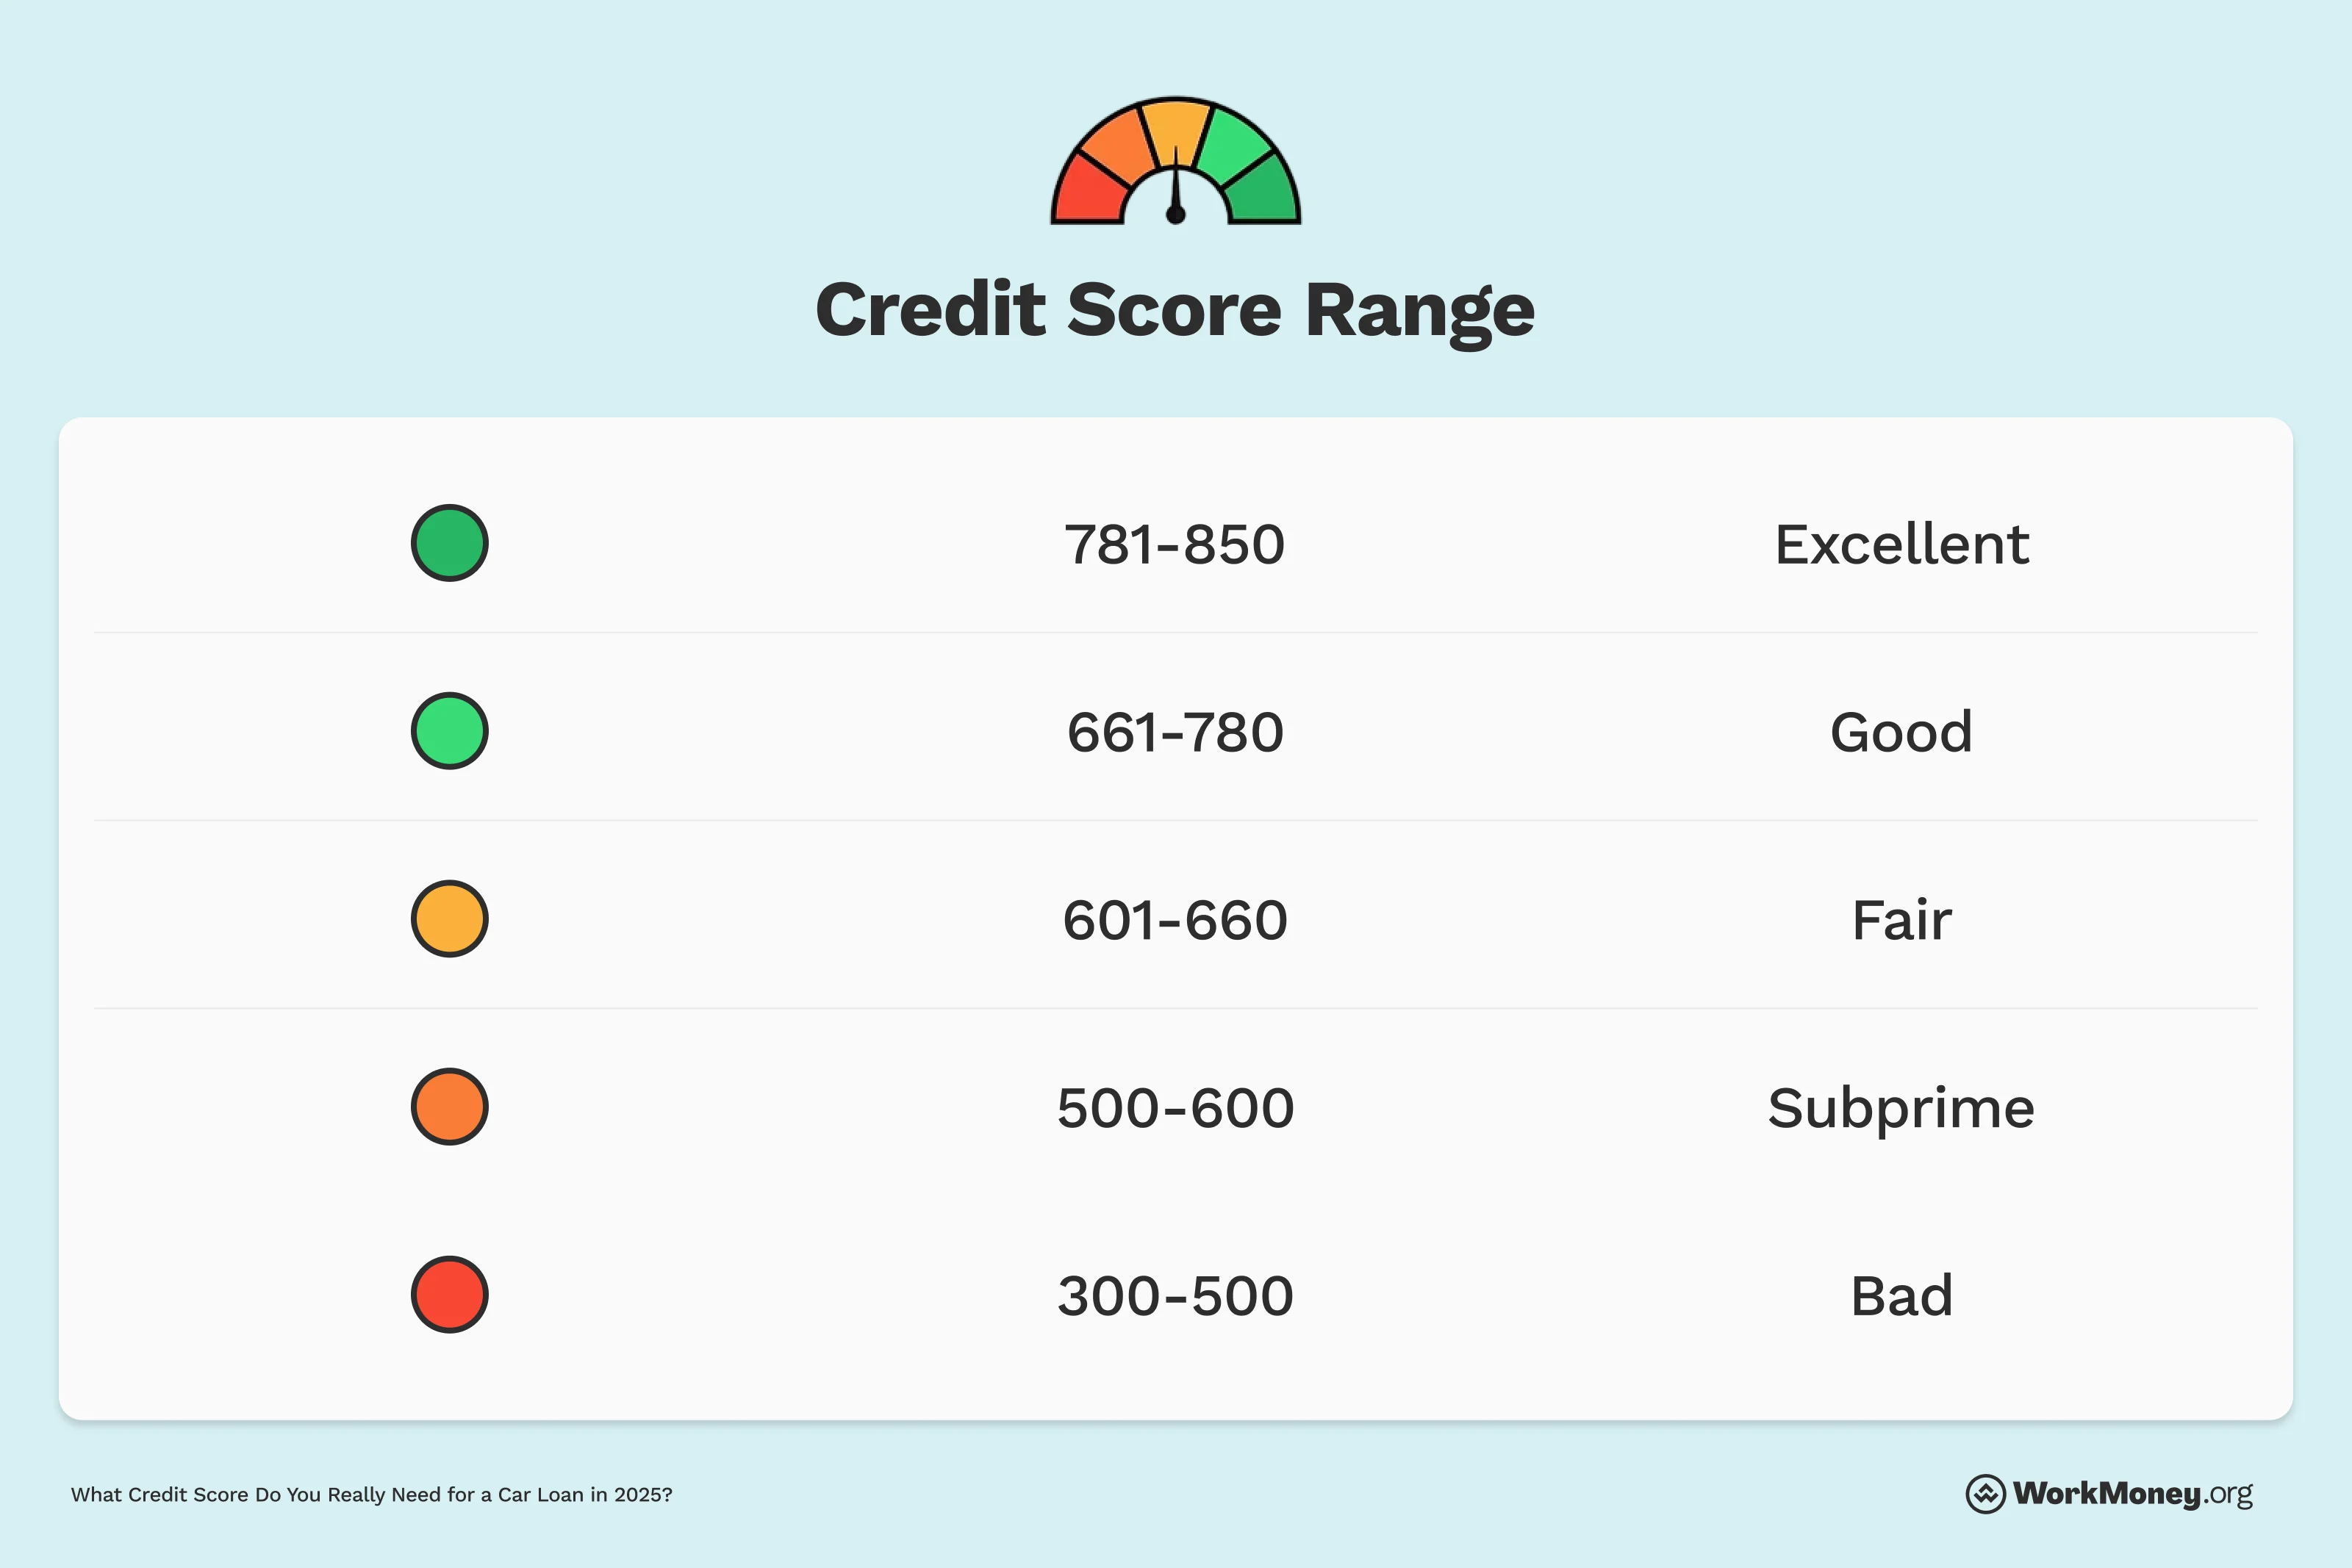
Before you step foot on a dealership lot or apply for online financing, it helps to understand how lenders evaluate a 597 FICO score. Credit scores range from 300 to 850. A score of 597 is considered poor. It typically stems from past financial challenges, such as late payments, high credit utilization, collections accounts, or perhaps a lack of extensive credit history.
When an auto lender pulls your credit report, they look at more than just the three-digit number. They also examine your:
- Debt-to-Income (DTI) Ratio: How much debt you owe compared to your gross monthly income.
- Employment Stability: Lenders want to see that you have held your current job for at least six months.
- Down Payment Capability: Cash upfront reduces the lender's financial risk.
- Recent Credit Behavior: Have you missed any payments in the last 3 to 6 months, or are your negative marks older?
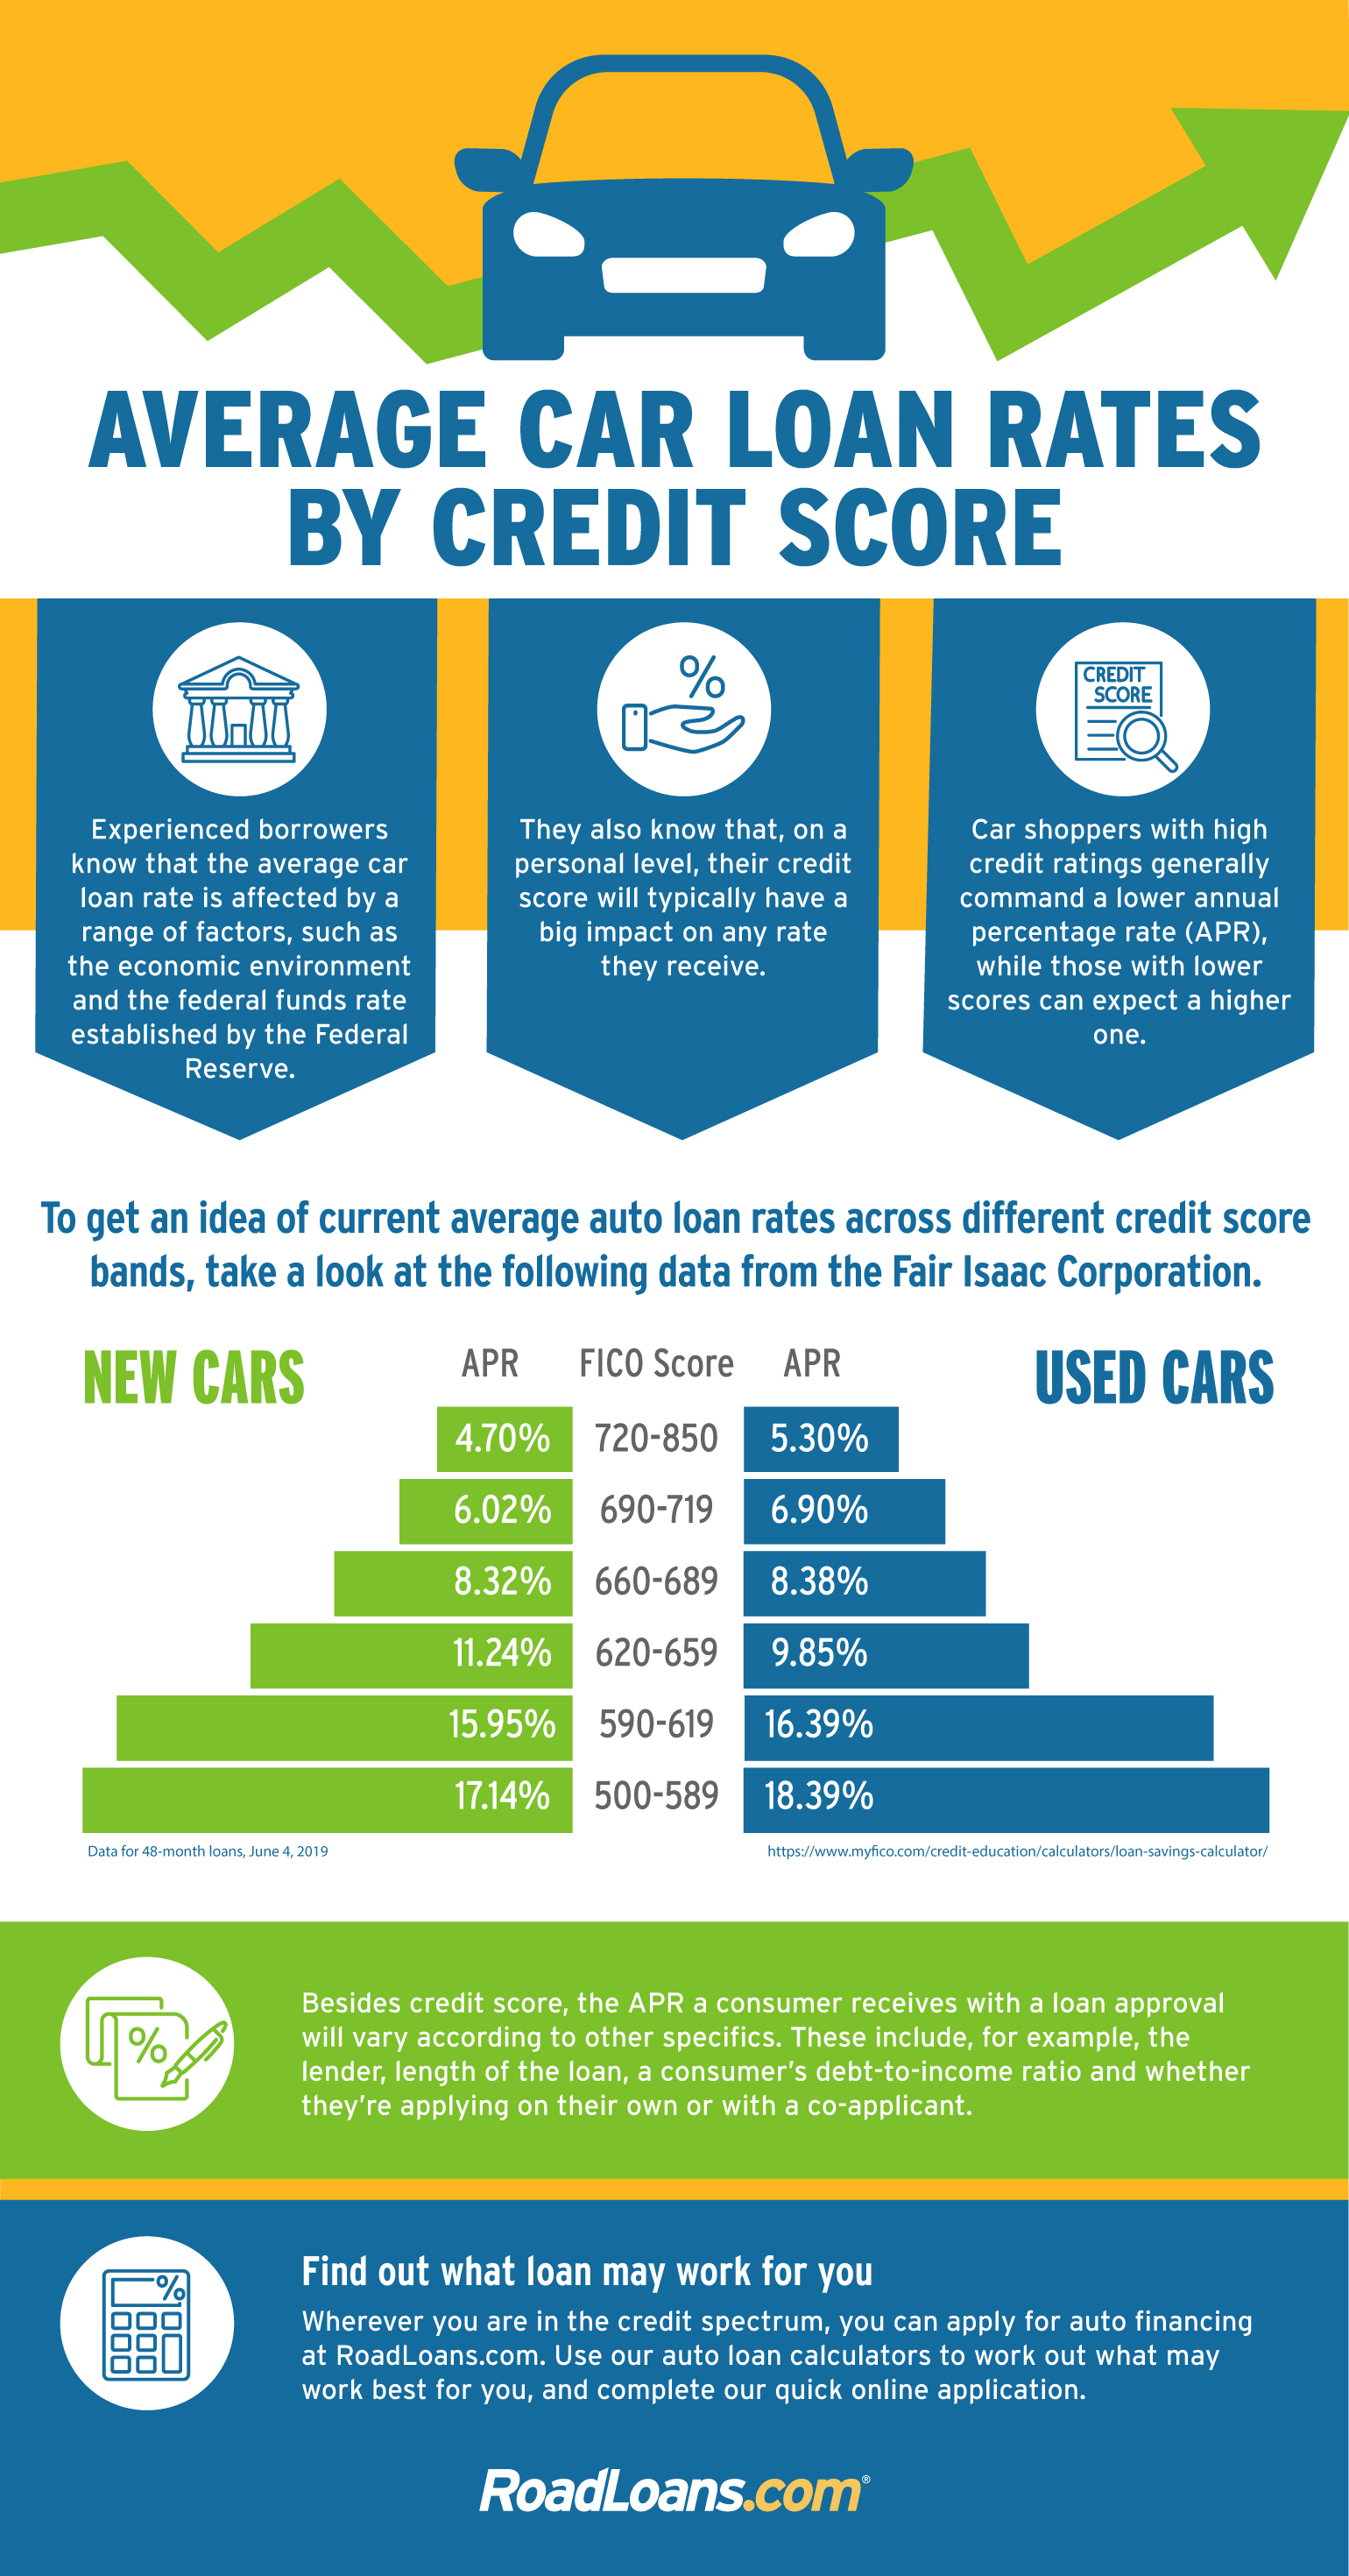
Because your score is below the prime threshold (which generally starts around 660 or 670), expect to pay a higher Annual Percentage Rate (APR). While a prime borrower might secure a loan with a 4% to 6% interest rate, a subprime borrower with a 597 score could see rates ranging from 12% to over 20% depending on income and down payment.
How to Qualify for a Car Loan With Bad Credit
Getting approved with a subprime score is straightforward if you meet basic lender requirements. To maximize your chances of approval and secure the best possible terms, follow these steps:
1. Check Your Credit Report First
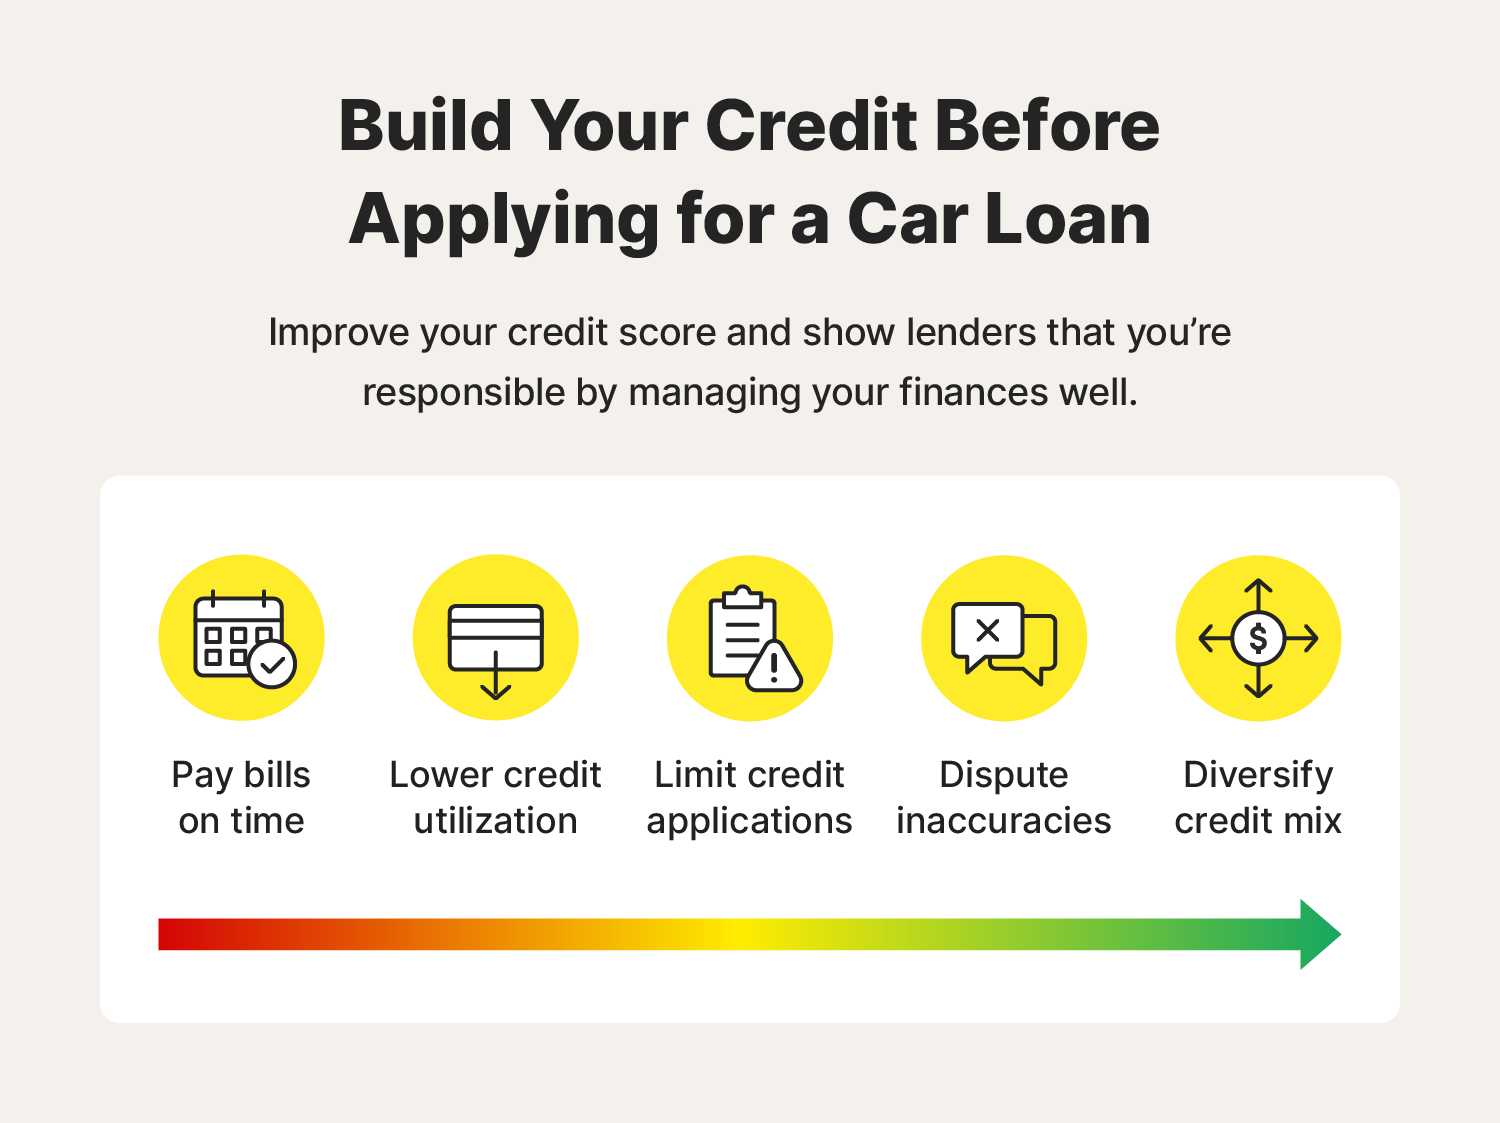
Never assume your credit score is accurate without checking. Pull your free credit reports from AnnualCreditReport.com. Look for errors, such as a paid collection still listed as unpaid or accounts that do not belong to you. Disputing and removing these errors can sometimes bump your score out of the subprime range before you even apply for a loan.
2. Save for a Substantial Down Payment
When lenders view you as high risk, offering a large down payment is your best negotiating tool. Aiming to put down 10% to 20% of the vehicle’s purchase price accomplishes two vital things:
- It instantly lowers the total amount you need to borrow, reducing your monthly payment.
- It proves to the lender that you have skin in the game, making them far more likely to approve your application.
3. Get Prequalified with Multiple Lenders
Do not rely solely on the dealership's finance department. Check with your local credit union, community bank, and online auto lenders to see what rates you prequalify for. Credit unions are particularly well-known for working with members who have lower credit scores, often offering lower rates than national commercial banks.
Tip: Try to submit all your auto loan applications within a focused 14-to-45-day window. Credit scoring models treat multiple auto loan inquiries within this timeframe as a single inquiry, minimizing any temporary damage to your score.
4. Consider a Cosigner
If you have a trusted family member or friend with good or excellent credit who is willing to cosign the loan, your 597 score will matter much less. The lender will evaluate the cosigner's income and credit score alongside yours. Keep in mind, however, that the cosigner shares legal responsibility for the loan. If you miss a payment, their credit score takes a hit too.
Choosing the Right Vehicle
When shopping with a 597 credit score car loan, your choice of vehicle can make or break your budget. High interest rates mean that financing an expensive car will result in astronomical monthly payments and severe total interest costs.
Focus on reliable, fuel-efficient, pre-owned cars, trucks, or SUVs that fit a strict budget. Dealerships may try to push you toward newer, higher-priced models because they are easier to finance through captive lenders, but sticking to a sensible vehicle priced under $15,000 to $18,000 will protect your financial health.
Red Flags to Avoid
Unfortunately, subprime borrowers are frequently targeted by predatory lenders and unscrupulous dealerships. Watch out for these common warning signs:
- "Everyone Approved" or "No Credit Check" Lots: These buy-here-pay-here dealerships often charge exorbitant interest rates (sometimes the legal maximum) and install GPS tracking or starter-interrupt devices on the vehicle.
- Focusing Only on Monthly Payments: Shady salespeople will ask, "What monthly payment fits your budget?" and then stretch the loan term out to 72 or 84 months to make it fit. This leaves you paying vastly more in total interest and risking negative equity (being "upside down" on your car loan).
- Mandatory Add-ons: Read the final contract carefully to ensure unwanted extended warranties, GAP insurance, or paint protection packages haven't been quietly rolled into your financed amount.
Refinancing Your Car Loan Later
A car loan with a 597 credit score does not have to be permanent. One of the smartest ways to handle subprime financing is to use the loan as a stepping stone to rebuild your credit.
Make every single monthly payment on time, without exception. Payment history makes up 35% of your FICO score. Within 12 to 18 months of consistent, on-time payments—combined with paying down your overall debt—your credit score will rise. Once your score crosses into the mid-to-high 600s, you can shop around to refinance the auto loan at a significantly lower interest rate, reducing your monthly payment and saving hundreds or thousands of dollars over the life of the loan.