Chase Morgan CD Rates: Worth It in Today's Market?
When looking for a secure place to park your cash, certificates of deposit (CDs) often come to mind. If you bank with Chase—or have looked into their premium relationship tiers through J.P. Morgan—you have likely wondered about chase morgan cd rates and whether they offer a competitive return for your hard-earned money.

Navigating the various tiers of Chase Bank and J.P. Morgan can be confusing. While standard retail deposit rates at major traditional banks are often modest, relationship tiers and specialized offerings can change the math. Here is a comprehensive breakdown of how Chase Morgan CD rates work, the terms available, and whether locking in your money here makes financial sense.
Understanding Chase and J.P. Morgan CD Options
Before diving into specific yields, it helps to understand the structure. Chase Bank and its wealth management arm, J.P. Morgan, cater to everyone from everyday retail savers to high-net-worth clients. Because of this, CD availability and pricing often depend on your account balance and your overall banking relationship.
Standard vs. Relationship Rates
Chase typically offers two main tiers of CD rates:
- Standard CD Rates: Available to any customer opening a standard retail certificate of deposit. These rates are generally quite low, mirroring the baseline yields offered by most brick-and-mortar mega-banks.
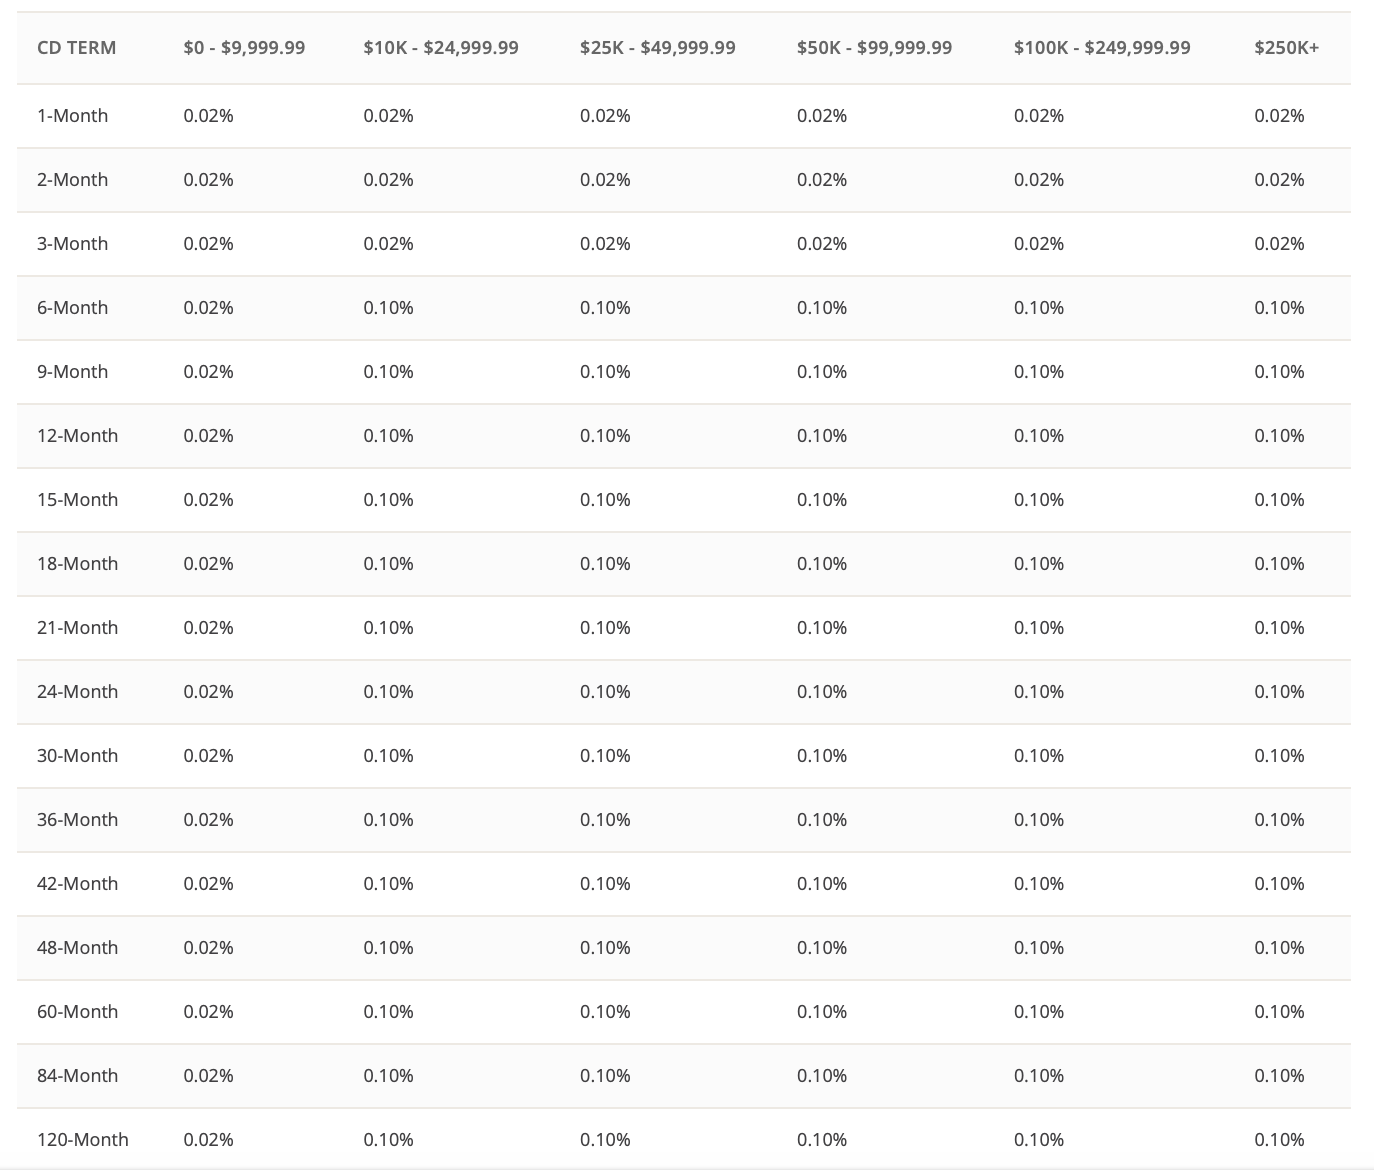
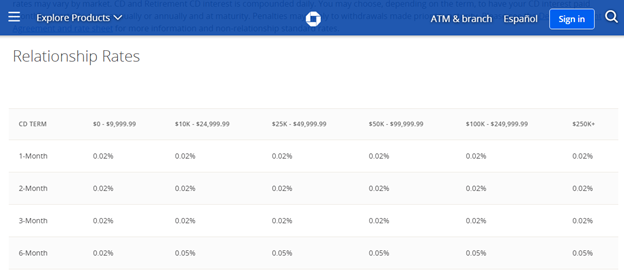
- Relationship CD Rates: Available if you link your CD to an eligible Chase checking account (such as Chase Premier Plus Checking or Chase Sapphire Checking). These rates are slightly higher than standard offers, though still typically lag behind dedicated online banks.
J.P. Morgan Wealth Management Tiers
For clients with significant assets under management through J.P. Morgan, customized deposit solutions and promotional CD rates may be available. These are rarely advertised publicly and are usually negotiated directly with a dedicated financial advisor based on your total portfolio size.
Current Trends in Chase Morgan CD Rates
Major national banks like Chase approach the interest rate environment conservatively. When the Federal Reserve raises or lowers interest rates, Chase adjusts its retail deposit yields at its own pace. Historically, standard chase morgan cd rates do not always match the peak APYs (Annual Percentage Yields) offered by digital-only banks or credit unions.
However, Chase frequently runs limited-time promotional CDs for specific terms—most commonly 3-month, 6-month, or 12-month durations—to attract new deposits. If you catch a promotional window and qualify for a relationship bump, the yield can be much closer to market averages for traditional banks.
Key Features of Chase CDs
Choosing a certificate of deposit involves more than just the headline APY. Here are the core features you can expect when opening a CD through Chase or J.P. Morgan:
- Minimum Deposit Requirements: Standard Chase CDs typically require a minimum opening deposit of $1,000, making them accessible to most savers. Promotional or specialized J.P. Morgan tiers may require higher minimums, sometimes starting at $10,000 or more.
- Term Lengths: Chase offers a variety of terms ranging from as short as one month up to 10 years, giving you flexibility depending on your liquidity needs.
- FDIC Insurance: Deposits held with Chase Bank are FDIC-insured up to $250,000 per depositor, per ownership category, providing complete security for your principal.
- Auto-Renewal Policy: When a Chase CD reaches maturity, you have a 10-day grace period to withdraw funds or change terms. If you take no action, the CD automatically renews for the same term at the current prevailing interest rate.
Pros and Cons of Investing with Chase
Before moving your money, weigh the distinct advantages and disadvantages of choosing Chase for your fixed-income savings.
The Advantages
Convenience: If you already use Chase for checking, credit cards, or a mortgage, keeping your savings in the same app streamlines your financial life.
Physical Branch Access: Unlike online-only banks, Chase has thousands of physical branches nationwide. If you prefer face-to-face customer service, this is a major plus.
Stability: As one of the largest financial institutions in the world, Chase offers unmatched institutional stability.
The Drawbacks
Lower Base Yields: Standard chase morgan cd rates frequently fall below the national average and lag far behind online competitors.
Early Withdrawal Penalties: Like most banks, withdrawing your principal before the maturity date incurs a penalty—typically forfeiting a portion of the interest earned (ranging from 90 days to several hundred days of interest depending on the term length).
How Chase Compares to Online Competitors
When shopping for a CD, it is crucial to look at the broader market. Online-only banks and credit unions frequently offer significantly higher APYs on matching terms because they lack the overhead costs of maintaining physical brick-and-mortar branches.
For example, while a standard Chase relationship CD might offer a modest yield, online competitors often double or triple that return for the exact same duration. If maximizing passive income is your primary goal, a digital bank or a brokered CD through a brokerage account will usually outperform a standard retail bank offering.
Strategies for Maximizing Your Savings
If you decide that Chase fits your overall banking ecosystem, you can employ a few strategies to optimize your returns:
- Build a CD Ladder: Instead of locking all your cash into a single 1-year or 3-year term, split your money across multiple staggered terms (e.g., 3, 6, 9, and 12 months). This ensures regular access to cash as each CD matures.
- Qualify for Relationship Rates: Ensure your checking account is properly linked to qualify for the highest available tier before you fund the CD.
- Talk to an Advisor: If you hold significant wealth, speak with a J.P. Morgan advisor to see if unadvertised promotional rates or alternative fixed-income vehicles (like Treasury bills or municipal bonds) offer a better after-tax yield.
The Bottom Line
Examining chase morgan cd rates reveals a familiar story for traditional mega-banks: convenience and stability come at the cost of lower yields. While Chase and J.P. Morgan provide secure, FDIC-insured options with flexible terms and physical branch support, standard rates rarely lead the market. Savers prioritizing maximum interest growth will likely find better returns elsewhere, but those who value an all-in-one banking relationship may find Chase's promotional or relationship rates acceptable for a portion of their portfolio.