Colorado Health Insurance Deductibles and Copays
Navigating the healthcare marketplace can feel like learning a brand-new language. If you live in the Centennial State, understanding Colorado health insurance deductibles and copays is essential for managing your medical expenses and choosing the right plan during open enrollment.

Whether you purchase a plan through the state-sponsored exchange, Connect for Health Colorado, or receive coverage through an employer, your out-of-pocket expenses are primarily driven by a few key financial mechanisms. This guide breaks down these terms, explains how they interact, and offers practical tips for keeping your healthcare costs manageable.
The Building Blocks of Colorado Health Insurance Costs
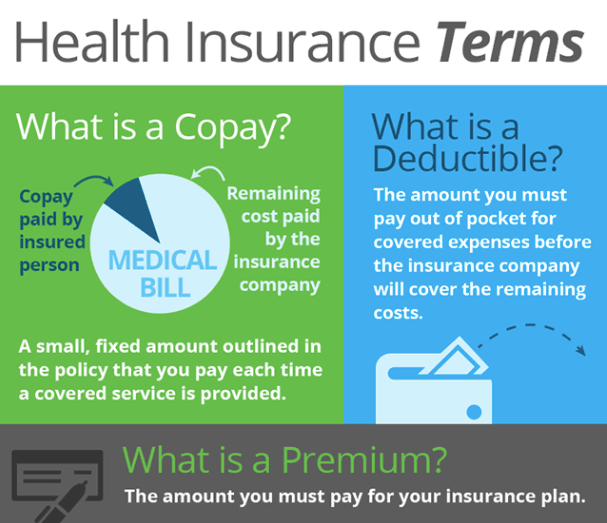
Before diving into specific cost-sharing terms, it helps to understand how a health insurance policy is structured. Every plan requires a monthly payment, known as a premium, to keep your coverage active. However, paying your premium does not mean your medical care is completely free.
When you visit a doctor, fill a prescription, or undergo a procedure, you typically share the cost with your insurance provider. The three most common ways you share these costs are through deductibles, copays, and coinsurance.
What is a Deductible?
A deductible is the amount of money you must pay out of your own pocket for medical care *before* your insurance company starts chipping in. For example, if your Colorado health plan has a $2,000 deductible, you are responsible for the first $2,000 of your covered medical expenses.
Keep in mind:
- Certain preventive services, such as annual physicals, routine vaccinations, and specific cancer screenings, are covered at 100% by most plans even if you haven't met your deductible yet, thanks to the Affordable Care Act.
- Family plans usually feature two deductibles: an individual deductible for each family member and an overall family deductible.
- Once you meet your deductible, you generally transition to paying copays or coinsurance for the remainder of the plan year.
Understanding Copays
A copay (or copayment) is a fixed dollar amount you pay for a specific medical service or prescription drug at the time you receive care. Unlike deductibles, copays are often required even if you have not met your annual deductible, though this depends entirely on your specific plan design.
Common examples of copays include:
- $20 to $40 for a standard primary care physician visit
- $50 to $75 for a specialist appointment
- $10 to $50 for generic or brand-name prescription drugs
- $150 to $500 for an urgent care or emergency room visit
Copays make budgeting predictable because you know exactly how much you will pay before walking into the clinic.

How Coinsurance Fits In
Coinsurance is closely related to copays, but instead of a flat fee, it is a percentage of the total medical bill. If your coinsurance rate is 20% and a medical procedure costs $1,000, you pay $200, and your insurance company pays the remaining $800. Coinsurance typically applies after you have met your deductible.
How Metal Tiers Affect Deductibles and Copays in Colorado
When shopping for a plan on Connect for Health Colorado, you will notice plans categorized by metal tiers: Bronze, Silver, Gold, and Platinum. These tiers do not reflect the quality of medical care; instead, they indicate how you and the insurance company split costs.
- Bronze Plans: Feature the lowest monthly premiums but the highest deductibles and out-of-pocket costs. These are typically chosen by young, healthy individuals who want catastrophic protection.
- Silver Plans: Offer moderate premiums and moderate deductibles. Importantly, if your household income qualifies you for federal subsidies, Silver plans are the only tier eligible for Cost-Sharing Reductions (CSRs), which actively lower your deductibles and copays.
- Gold Plans: Come with higher monthly premiums, but feature much lower deductibles and smaller copays. These are ideal for individuals with chronic conditions or those who anticipate frequent medical needs.
- Platinum Plans: Feature the highest monthly premiums and near-zero deductibles, with the insurance company covering the vast majority of medical costs.
The Safety Net: The Out-of-Pocket Maximum
No matter how high your medical bills climb, there is a legal limit to what you can be forced to pay in a single year. This is called the out-of-pocket maximum.
In Colorado, all Affordable Care Act-compliant health plans must cap your annual out-of-pocket spending. Once the total amount you have spent on deductibles, copays, and coinsurance reaches this threshold, your insurance company pays 100% of all covered medical services for the rest of the calendar year.
Understanding this limit provides profound financial peace of mind, protecting you from medical bankruptcy in the event of a severe accident or major illness.
Tips for Managing Your Healthcare Expenses in Colorado
Minimizing your medical expenditures requires strategy and awareness. Use these practical tips to make the most of your Colorado health insurance policy:
- Stay In-Network: Colorado insurance plans maintain strict networks of doctors, hospitals, and clinics. Visiting an out-of-network provider can result in significantly higher deductibles, or worse, denied coverage entirely. Always verify that your preferred provider is in-network.
- Utilize Preventive Care: Take advantage of free preventive services. Catching health issues early prevents costly emergency interventions down the road.
- Compare Prescription Formularies: Drug copays vary drastically between plans. Check the plan's formulary (its list of covered medications) to ensure your specific prescriptions are covered affordably.
- Explore Savings Accounts: If you enroll in a high-deductible health plan (HDHP), consider opening a Health Savings Account (HSA). Contributions are tax-deductible, and funds roll over year-to-year, helping you build a dedicated medical nest egg.
By understanding how deductibles, copays, and metal tiers function together, you can confidently select a Colorado health insurance plan that fits both your medical needs and your monthly budget.