Ditch Bad Money Habits Now
Money troubles rarely start with a single catastrophic event. Instead, they usually stem from a slow accumulation of daily financial leaks—small, unconscious choices that drain your bank account over time. If you are tired of living paycheck to paycheck or wondering where your hard-earned cash went at the end of every month, it is time for a change. When you need to ditch bad money habits – this personalfinance wiki has the answers to help you course-correct.

Transforming your financial life does not require an advanced degree in economics or a six-figure salary. It simply requires awareness, structure, and a willingness to replace toxic financial routines with intentional behaviors. Let us examine the most common financial pitfalls and the exact steps you can take to overcome them.
Recognizing the Root Causes of Financial Stress
Before you can fix your finances, you must understand why you make certain spending choices. Money is deeply emotional. Many people use spending as a temporary fix for stress, boredom, or anxiety—a phenomenon commonly known as retail therapy.
Others fall into lifestyle creep, automatically increasing their spending every time they get a raise. Recognizing these psychological triggers is the first step toward building a healthier relationship with money. When you pause to identify the emotion driving a purchase, you regain control over your wallet.
Ditch Bad Money Habits – This Personalfinance Wiki Has the Answers
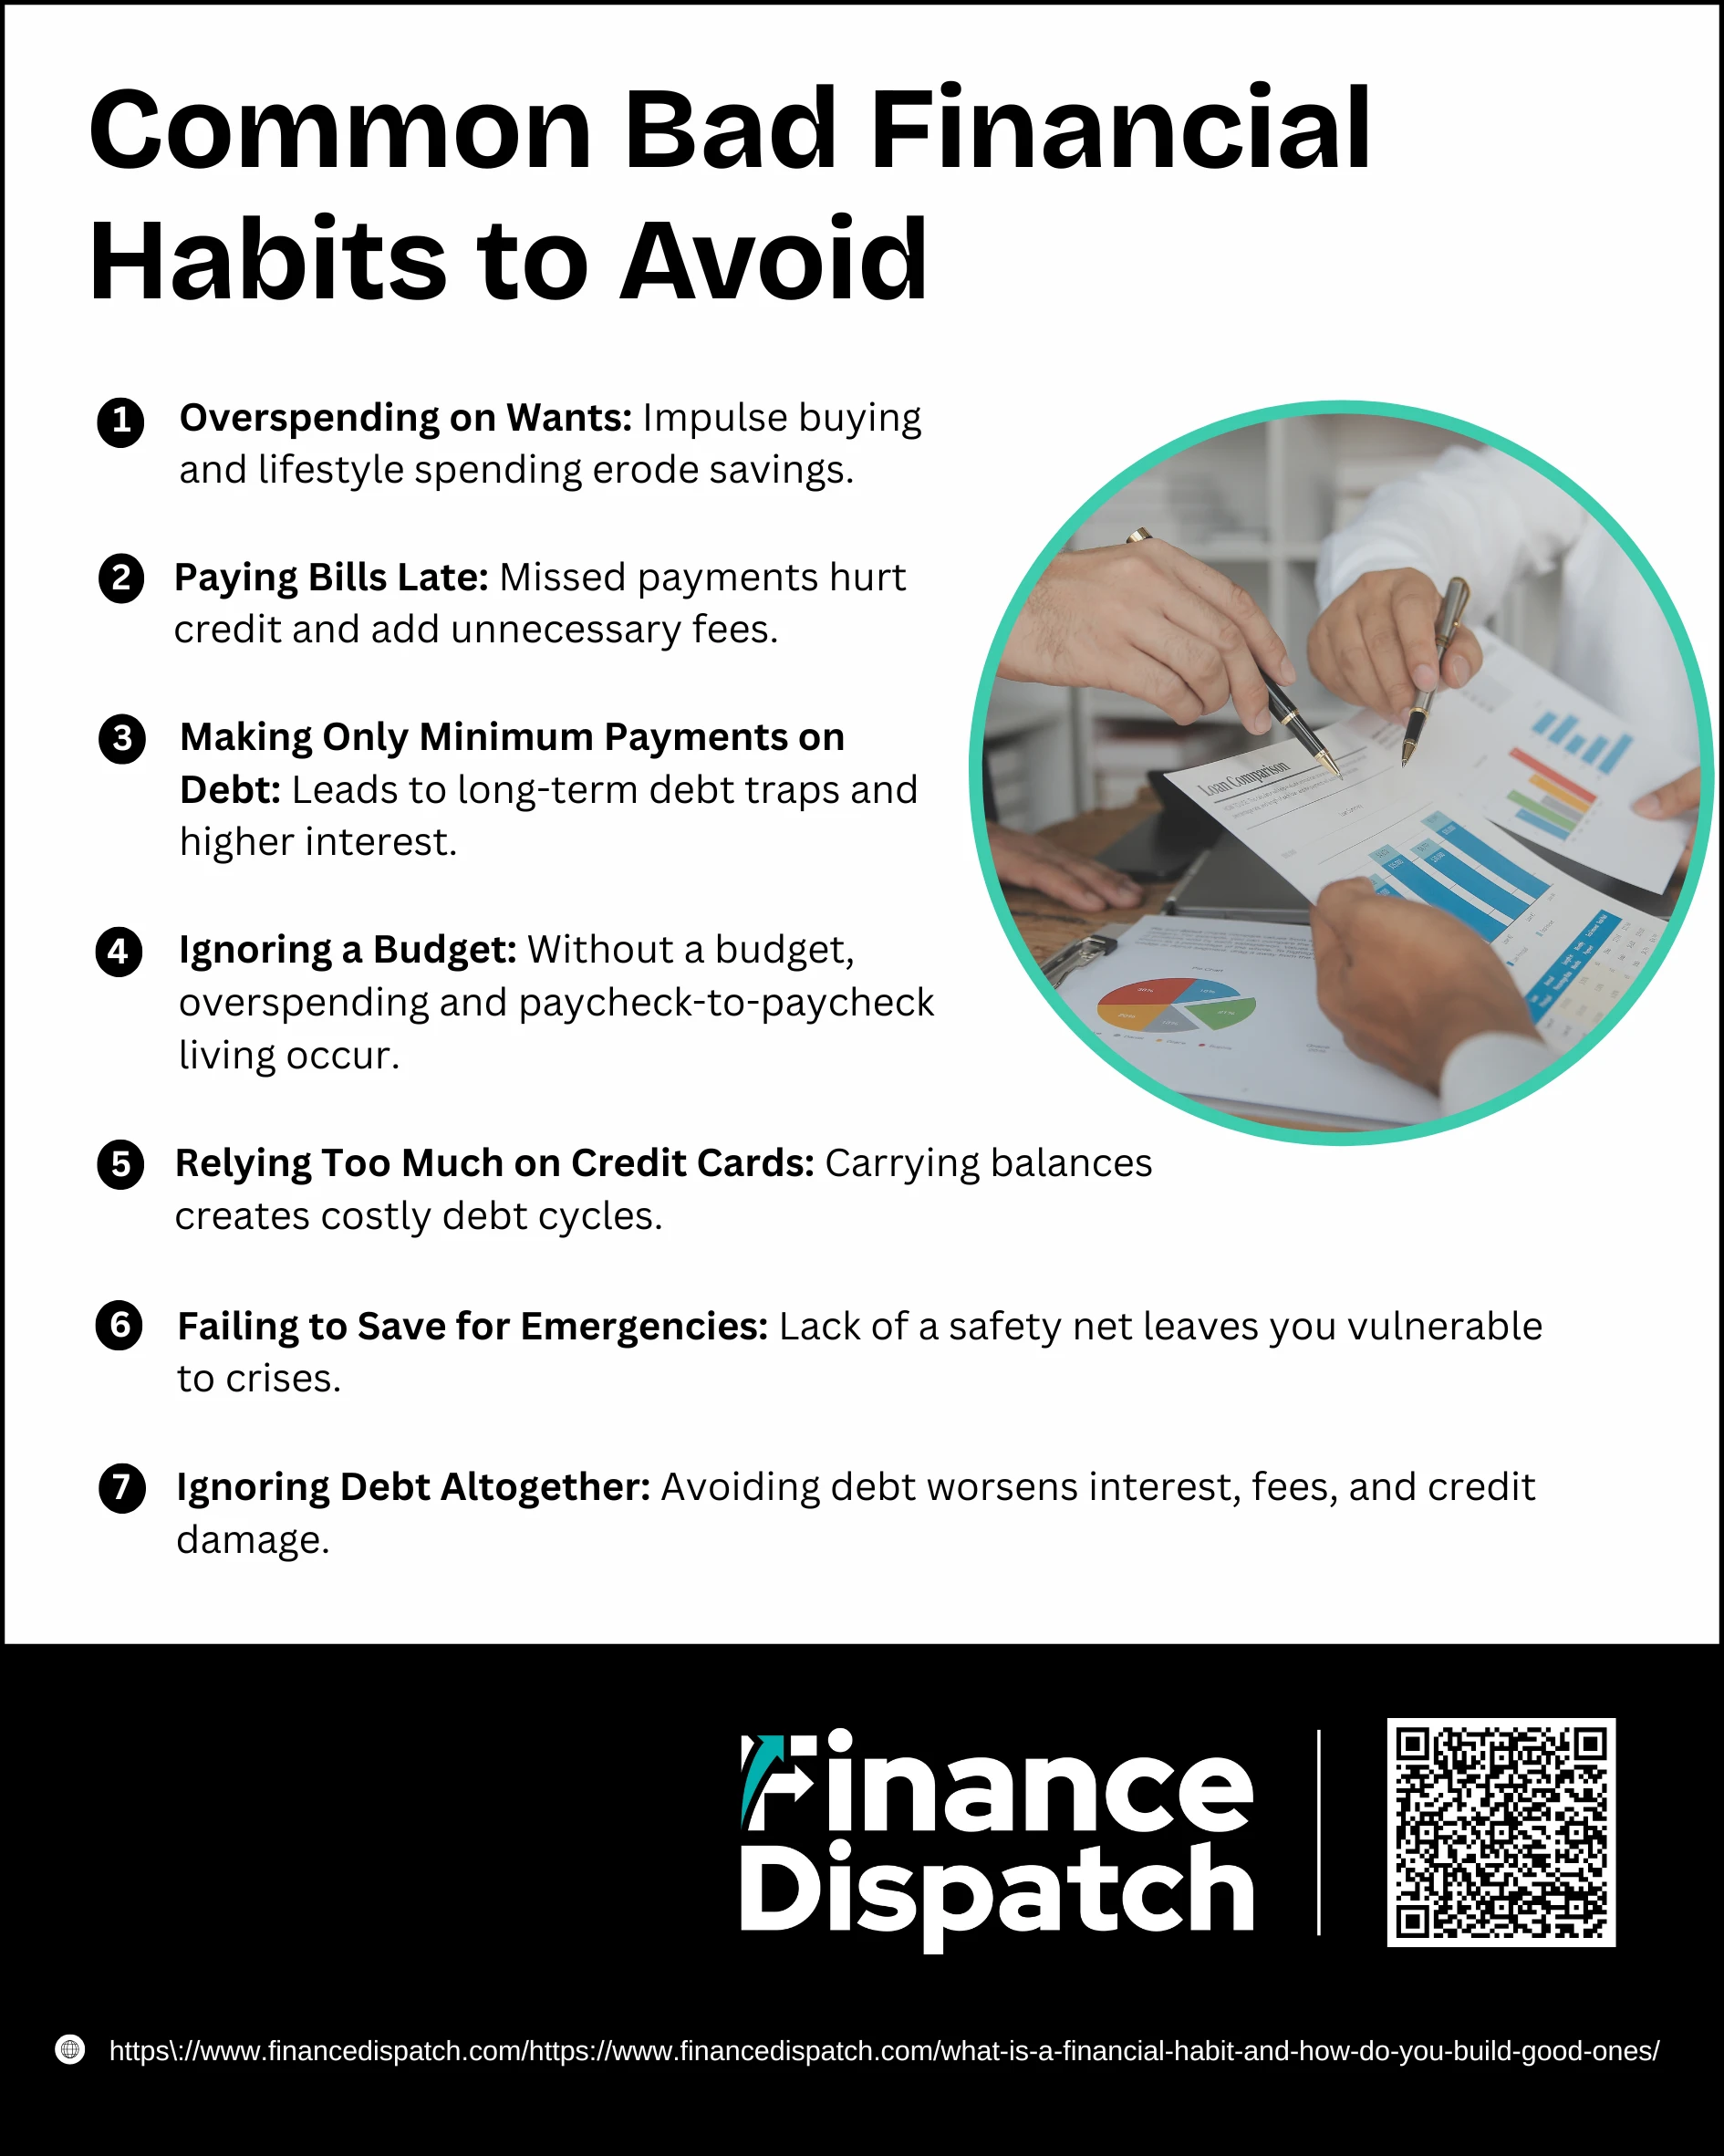
To build a secure financial foundation, you need actionable strategies that target the most damaging behaviors. Here is a breakdown of the core habits you need to break and what to do instead.
1. Mindless Spending and Subscription Creep
Many of us bleed money through subscriptions we no longer use, daily artisanal coffees we barely taste, and impulse purchases made late at night on our smartphones. These micro-transactions feel harmless in the moment, but they add up to thousands of dollars a year.
- Audit your bank statements: Go through the last 90 days of transactions and highlight every recurring subscription. Cancel anything you have not used in the past month.
- Implement a 48-hour rule: For any non-essential purchase over $50, force yourself to wait 48 hours before buying. Often, the urge passes.
- Automate your savings: Move money into a high-yield savings account the moment you get paid, making it harder to spend blindly.
2. Living Without a Budget
Operating without a budget is like driving across the country without a map or a GPS. You might move forward, but you have no guarantee you are heading in the right direction. A budget is not a restriction; it is simply a plan for your money that tells every dollar where to go.

Try the popular 50/30/20 framework to simplify your budgeting process:
- 50% for Needs: Housing, utilities, groceries, insurance, and minimum debt payments.
- 30% for Wants: Dining out, entertainment, hobbies, and vacations.
- 20% for Financial Goals: Extra debt payoff, emergency fund contributions, and investments.
3. Relying on High-Interest Debt
Carrying a balance on credit cards is one of the fastest ways to destroy your financial health. Credit card companies charge exorbitant interest rates, which means a small purchase can end up costing you double or triple its original price over time.
If you are trapped in a cycle of credit card debt, tackle it aggressively using one of two proven methods:
- The Debt Avalanche: Pay off the debt with the highest interest rate first while making minimum payments on the rest. This saves you the most money mathematically.
- The Debt Snowball: Pay off the smallest balance first for a quick psychological win, then roll that payment into the next-smallest debt.
4. Neglecting the Emergency Fund
Life is unpredictable. Cars break down, water heaters leak, and unexpected medical bills appear out of nowhere. Without an emergency fund, these minor crises instantly turn into major financial disasters that force you back into debt.
Start small if you must. Aim for a starter emergency fund of $1,000, and gradually build it up until you have three to six months' worth of essential living expenses tucked safely away in a separate savings account.
Building Long-Term Momentum
Breaking bad money habits is not a one-time event; it is an ongoing practice. As you implement these changes, give yourself grace for the occasional misstep. The goal is progress, not perfection.
Track your net worth monthly to watch your wealth grow. Celebrate small milestones, like paying off a credit card or hitting your first $5,000 in savings. By replacing careless financial behaviors with deliberate, goal-oriented actions, you will create lasting security and peace of mind.