Finding the Right Fixer Upper Property for Sale
Introduction to Buying a Project Home

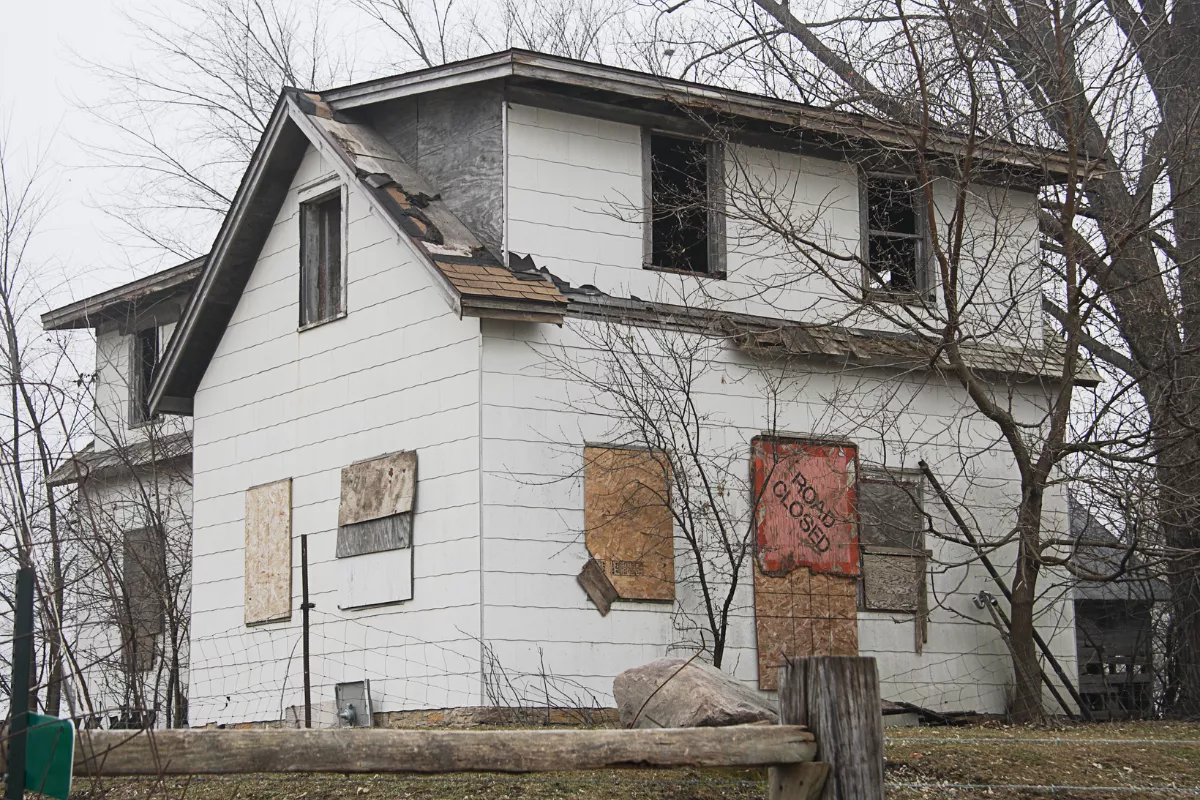
Hunting for a fixer upper property for sale is a thrilling venture for aspiring homeowners and seasoned real estate investors alike. Purchasing a house that needs work often means breaking into a desirable neighborhood at a lower price point, customizing every single room to your exact taste, and building instant equity once the renovations are complete.
However, buying a home that requires extensive repairs is vastly different from purchasing a move-in ready property. Without proper planning, meticulous budgeting, and professional inspections, a dream renovation can quickly spiral into a financial and emotional burden. This guide walks you through everything you need to know to successfully find, fund, and renovate a diamond in the rough.
Where to Find the Best Fixer Upper Property for Sale
Finding a property with good bones and high potential requires looking beyond standard real estate listings. While websites like Zillow and Realtor.com are great starting points, the most competitively priced properties often require a bit of digging.
Working with Specialized Real Estate Agents
Partnering with a local real estate agent who specializes in distressed properties, foreclosures, and estate sales can give you a massive advantage. These professionals often know about properties before they officially hit the market, or they can help you navigate the complexities of buying bank-owned homes and short sales.
Driving for Dollars and Local Auctions
Many great renovation candidates never make it to the digital market. Driving through your target neighborhoods to spot vacant homes, overgrown lawns, or houses with 'For Sale by Owner' signs can unearth hidden gems. Additionally, local county sheriff sales and tax auctions frequently list properties well below market value, though these usually require cash purchases and carry higher risks.
Evaluating Structural Integrity vs. Cosmetic Flaws
Before making an offer on any fixer upper property for sale, you must learn to distinguish between cheap cosmetic updates and costly structural nightmares. While bold paint colors, ugly carpet, and outdated 1970s cabinetry are easy fixes, hidden problems can destroy your renovation budget.
- Cosmetic Fixes (Low Risk): Painting walls, replacing light fixtures, updating hardware, laying new flooring, and swapping out vanities. These are DIY-friendly or inexpensive for a contractor to handle.
- Functional Updates (Moderate Risk): Updating outdated electrical panels, replacing old plumbing lines, installing a new HVAC system, or putting on a new roof. These require licensed professionals and a healthy budget.
- Structural Issues (High Risk): Foundation cracks, sagging rooflines, severe water damage, termite infestations, and mold remediation. These problems can cost tens of thousands of dollars and often reveal more damage once walls are opened up.
Financing Your Renovation Project
Video: How to Sell a Fixer Upper Home
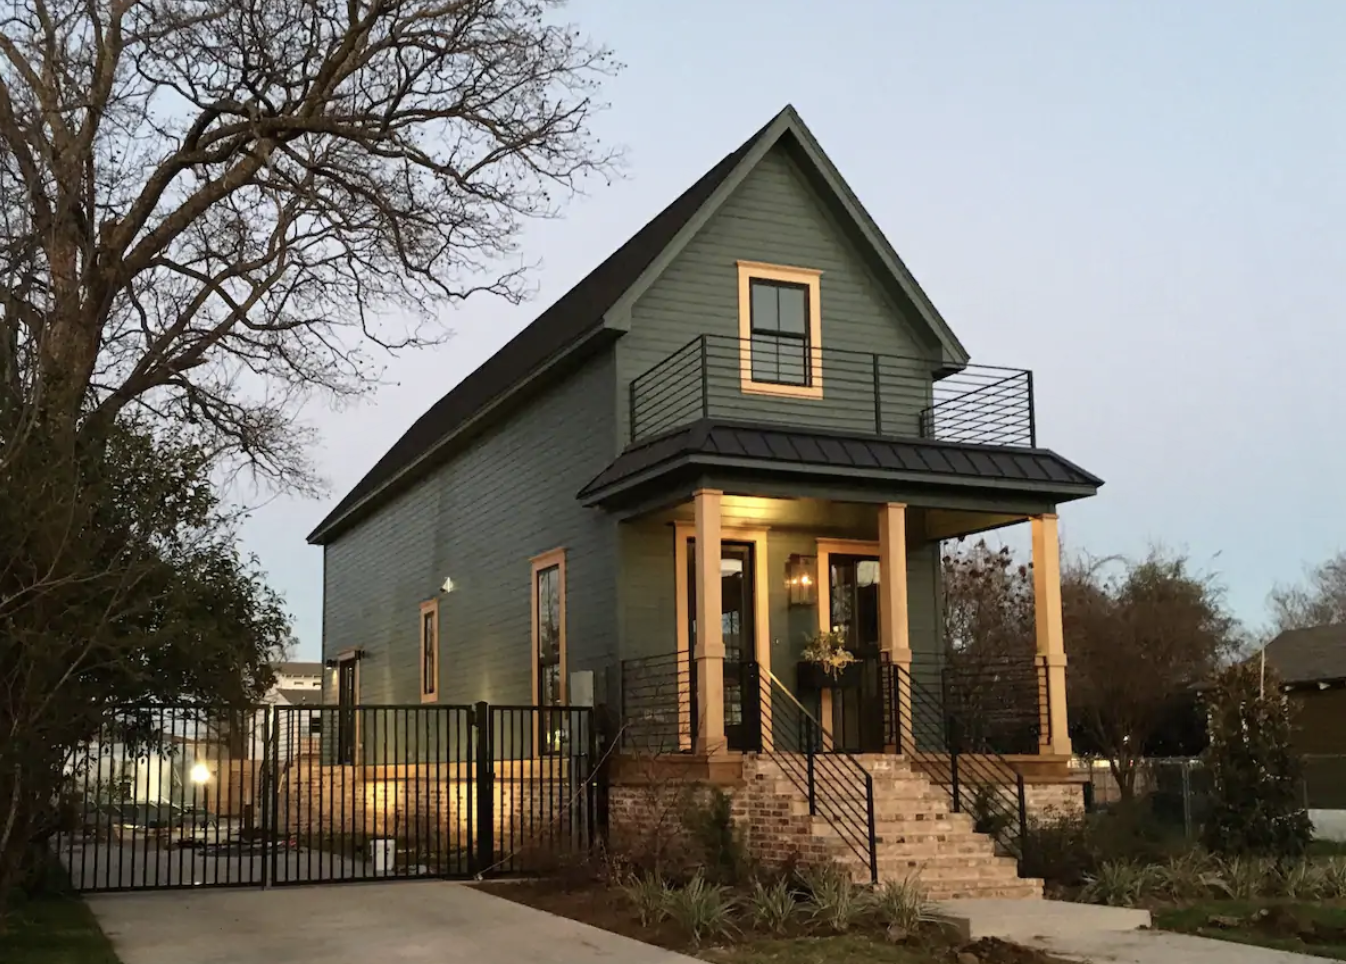
Traditional mortgages only cover the purchase price of a home, leaving buyers wondering how to pay for the materials and labor needed to make it habitable. Fortunately, several specialized loan products are designed specifically for buyers purchasing a fixer upper property for sale.
FHA 203(k) Loans
The FHA 203(k) loan allows borrowers to finance both the purchase of a home and the cost of its rehabilitation through a single mortgage. There are two main types: the Limited 203(k) for minor remodeling projects up to $35,000, and the Standard 203(k) for major structural renovations.
Fannie Mae HomeStyle Renovation Mortgages
Similar to the FHA 203(k), the HomeStyle loan provides financing for home improvements bundled into a conventional mortgage. It offers flexible borrowing limits and can be used on primary residences, second homes, and even investment properties.
Home Equity Loans and Lines of Credit (HELOC)
If you already own a home with significant equity, you can tap into that equity to purchase and renovate your fixer upper property. This method often appeals to cash buyers or those who want to avoid the strict contractor requirements of government-backed renovation loans.
Building a Realistic Renovation Budget
One of the golden rules of real estate is to calculate your anticipated renovation costs and then add a 20% to 30% contingency buffer. Unexpected surprises are practically guaranteed when renovating older homes. Whether an electrician discovers knob-and-tube wiring behind the drywall or you find water damage beneath the subfloor, having a financial safety net is critical.
Always secure multiple bids from licensed, insured contractors before closing on the property. Never rely on ballpark estimates found online, as material and labor costs vary significantly by region.
Conclusion: Is a Fixer Upper Right for You?
Taking on a fixer upper property for sale requires patience, resilience, and financial discipline. For those willing to put in the hard work, the payoff is immense: a custom home tailored to your lifestyle and the potential for substantial financial reward. By carefully vetting properties, securing the right financing, and budgeting for the unexpected, you can turn a neglected house into your forever home.