How the Founder of Cash App Built a Billion-Dollar Giant
Introduction: The Genesis of a Mobile Payment Titan

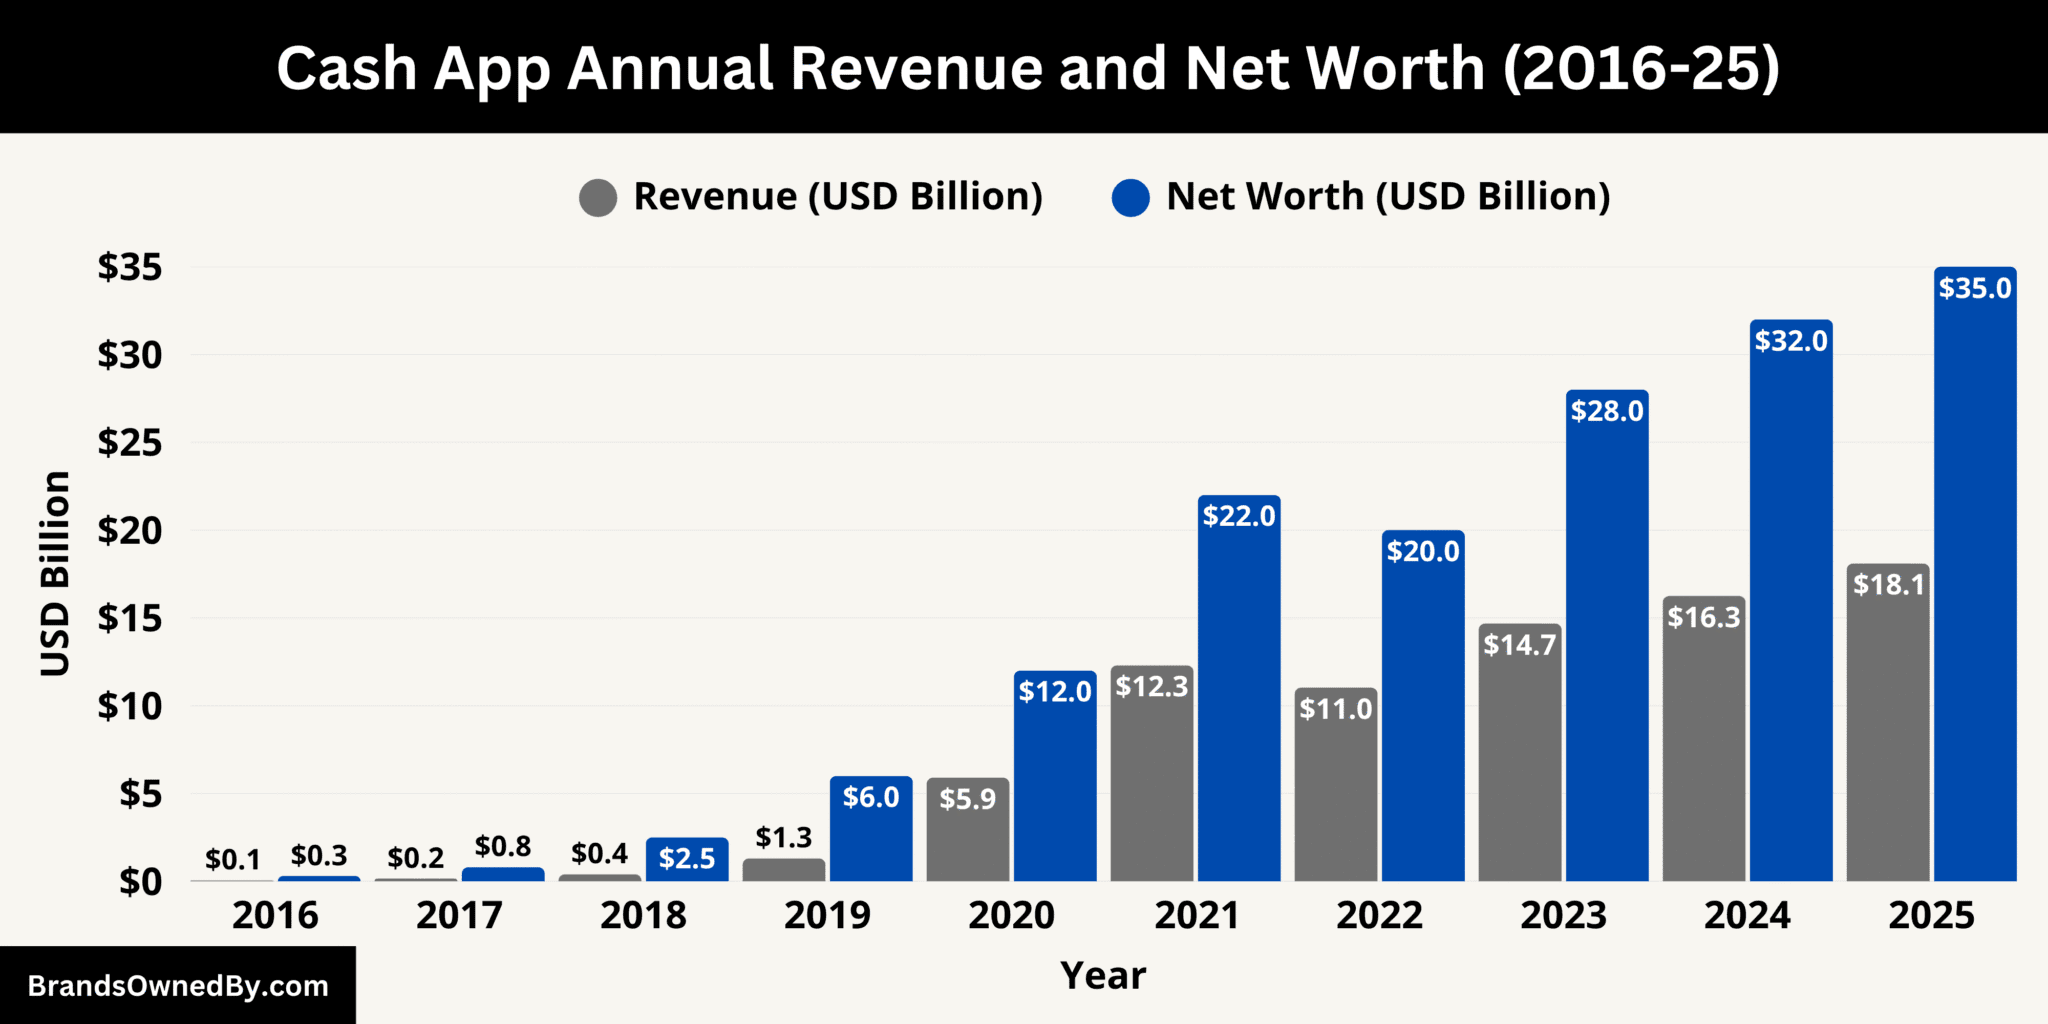
In a little over a decade, mobile peer-to-peer (P2P) payments transformed from a clunky novelty into the financial operating system for hundreds of millions of people. At the center of this revolution is Cash App, a product born out of Jack Dorsey and Brian Amerigo’s larger ecosystem at Square (now Block, Inc.). Understanding **how the founder of Cash App built a cash machine that pays out over $billions!** requires looking at a masterclass in minimalist product design, viral growth loops, and aggressive ecosystem expansion.
Rather than trying to build a traditional digital bank from day one, the team focused on friction reduction. They solved a hyper-specific annoyance: splitting bills and paying friends without needing cash, checks, or cumbersome bank routing numbers. Today, that singular focus generates billions in gross profit, handles massive transaction volumes, and has redefined consumer finance.
From Square to Square Cash: The Origin Story
When Square launched in 2009, it solved credit card acceptance for small merchants using a tiny white card reader plugged into a smartphone headphone jack. While merchants loved it, Jack Dorsey and his product teams noticed an adjacent opportunity in consumer-to-consumer transactions.
In 2013, Square launched "Square Cash" (later rebranded simply as Cash App). The initial value proposition was radical in its simplicity: users could send money via email. You didn't even need a password or a complex account setup. You simply typed the amount, added $cashtag, and hit send.
The Strategic Pivot to a Consumer Hub
Early on, competing with established giants like PayPal’s Venmo seemed daunting. However, Cash App differentiated itself by focusing on speed and accessibility. While Venmo leaned heavily into a public social feed (which many users found intrusive or unnecessary), Cash App kept transactions private, fast, and strictly functional.
This focus on privacy and speed laid the groundwork for user trust. Once millions of users trusted the app to hold and transfer small amounts of cash, the platform was positioned to introduce high-margin financial services.
The Engine Room: How Cash App Generates Billions
A P2P payment app on its own is historically difficult to monetize directly. Charging fees to send money to friends usually kills user adoption. So, how did the platform scale into a multi-billion-dollar revenue engine? It diversified its revenue streams by turning a utility app into a full-fledged neobank.
1. The Cash Card and Interchange Fees
One of the most powerful monetization levers was the introduction of the Cash Card—a customizable debit card linked directly to a user's Cash App balance. Every time a user swipes their physical or virtual Cash Card at a merchant, the merchant pays an interchange fee. Because millions of consumers use the Cash Card for daily coffee runs, grocery shopping, and gas, these micro-transactions add up to hundreds of millions of dollars in steady revenue.

2. Instant Deposit Fees
Traditional bank transfers typically take two to three business days to clear. Cash App introduced an "Instant Deposit" feature that allows users to move money to their debit cards immediately for a small percentage fee (usually 0.5% to 1.75%). For gig economy workers, freelancers, and anyone needing immediate liquidity, paying a small fee for instant access is a worthwhile trade-off.
3. Bitcoin Trading and Brokerage
In 2018, Cash App integrated Bitcoin trading, allowing users to buy and sell cryptocurrency with just a few taps. By taking a small spread on every trade, the app captured the massive wave of retail crypto enthusiasm. During peak market cycles, Bitcoin trading alone drove massive transaction volumes and revenue spikes.
4. Cash App Investing
Following the crypto rollout, the platform launched fractional share investing, allowing users to buy stock in major companies (like Apple, Tesla, or Amazon) with as little as $1. This opened up stock market investing to younger, lower-income demographics who previously found traditional brokerages intimidating or too expensive.
The Viral Growth Playbook
Building a great product is only half the battle; getting people to use it requires relentless distribution. Cash App employed several innovative marketing and growth loops that drove down customer acquisition costs (CAC).
- Peer-to-Peer Virality: Every time a user pays someone who doesn't have the app, a natural invitation is sent. The product is its own best marketer.
- The $Cashtag: Instead of asking for long account numbers, users shared simple, memorable handles (e.g., $JaneDoe). This branding became ubiquitous across social media.
- Social Media Giveaways (#CashAppFriday): The company leveraged Twitter (now X) and Instagram brilliantly, running viral promotional campaigns where users shared their $Cashtags for a chance to win cash prizes. This turned everyday users into brand advocates.
- Influencer Partnerships: Long before traditional banks understood creator marketing, Cash App was partnering with hip-hop artists, streamers, and internet creators who organically integrated the app into their lifestyles and lyrics.
Lessons for Modern Entrepreneurs
The success of the platform offers a blueprint for building high-growth fintech companies today. Founders looking to replicate this trajectory can study several core principles:
- Solve One Pain Point Flawlessly: Start with a single, frictionless feature that hooks the user before overwhelming them with secondary services.
- Build a Closed-Loop Ecosystem: Once you own the consumer's primary interface, layer on adjacent financial products (cards, investing, crypto) to increase lifetime value (LTV).
- Embrace Non-Traditional Marketing: Traditional banking ads are sterile and boring. Cash App won by meeting its demographic where they spent time—social media and pop culture.
Conclusion
The journey from a simple peer-to-peer money transfer tool to a multi-billion-dollar fintech powerhouse is a testament to disciplined product evolution. By removing the friction of traditional banking, leaning into internet culture, and stacking high-margin financial products onto a loyal user base, the creators of Cash App built a modern financial empire. It remains one of the defining business success stories of the digital economy.