Jeb Robertson’s Financial Resilience: $60M in a Decade
Building lasting wealth is rarely a linear journey. While speculative bubbles and overnight windfalls capture public attention, true financial independence is usually forged through systemic discipline, risk management, and the ability to adapt when market conditions sour. The story behind Jeb Robertson’s Financial Resilience – $60 Million Achieved in Less Than a Decade! highlights how an entrepreneur and private investor moved from foundational setbacks to creating an enduring, diversified portfolio valued at eight figures in fewer than ten years.

Rather than relying on luck or short-lived market trends, Robertson engineered a repeatable playbook based on capital reinvestment, asymmetric upside, and operational leverage. By studying the mechanics of this rapid turnaround, modern entrepreneurs and private investors can glean actionable insights for their own balance sheets.
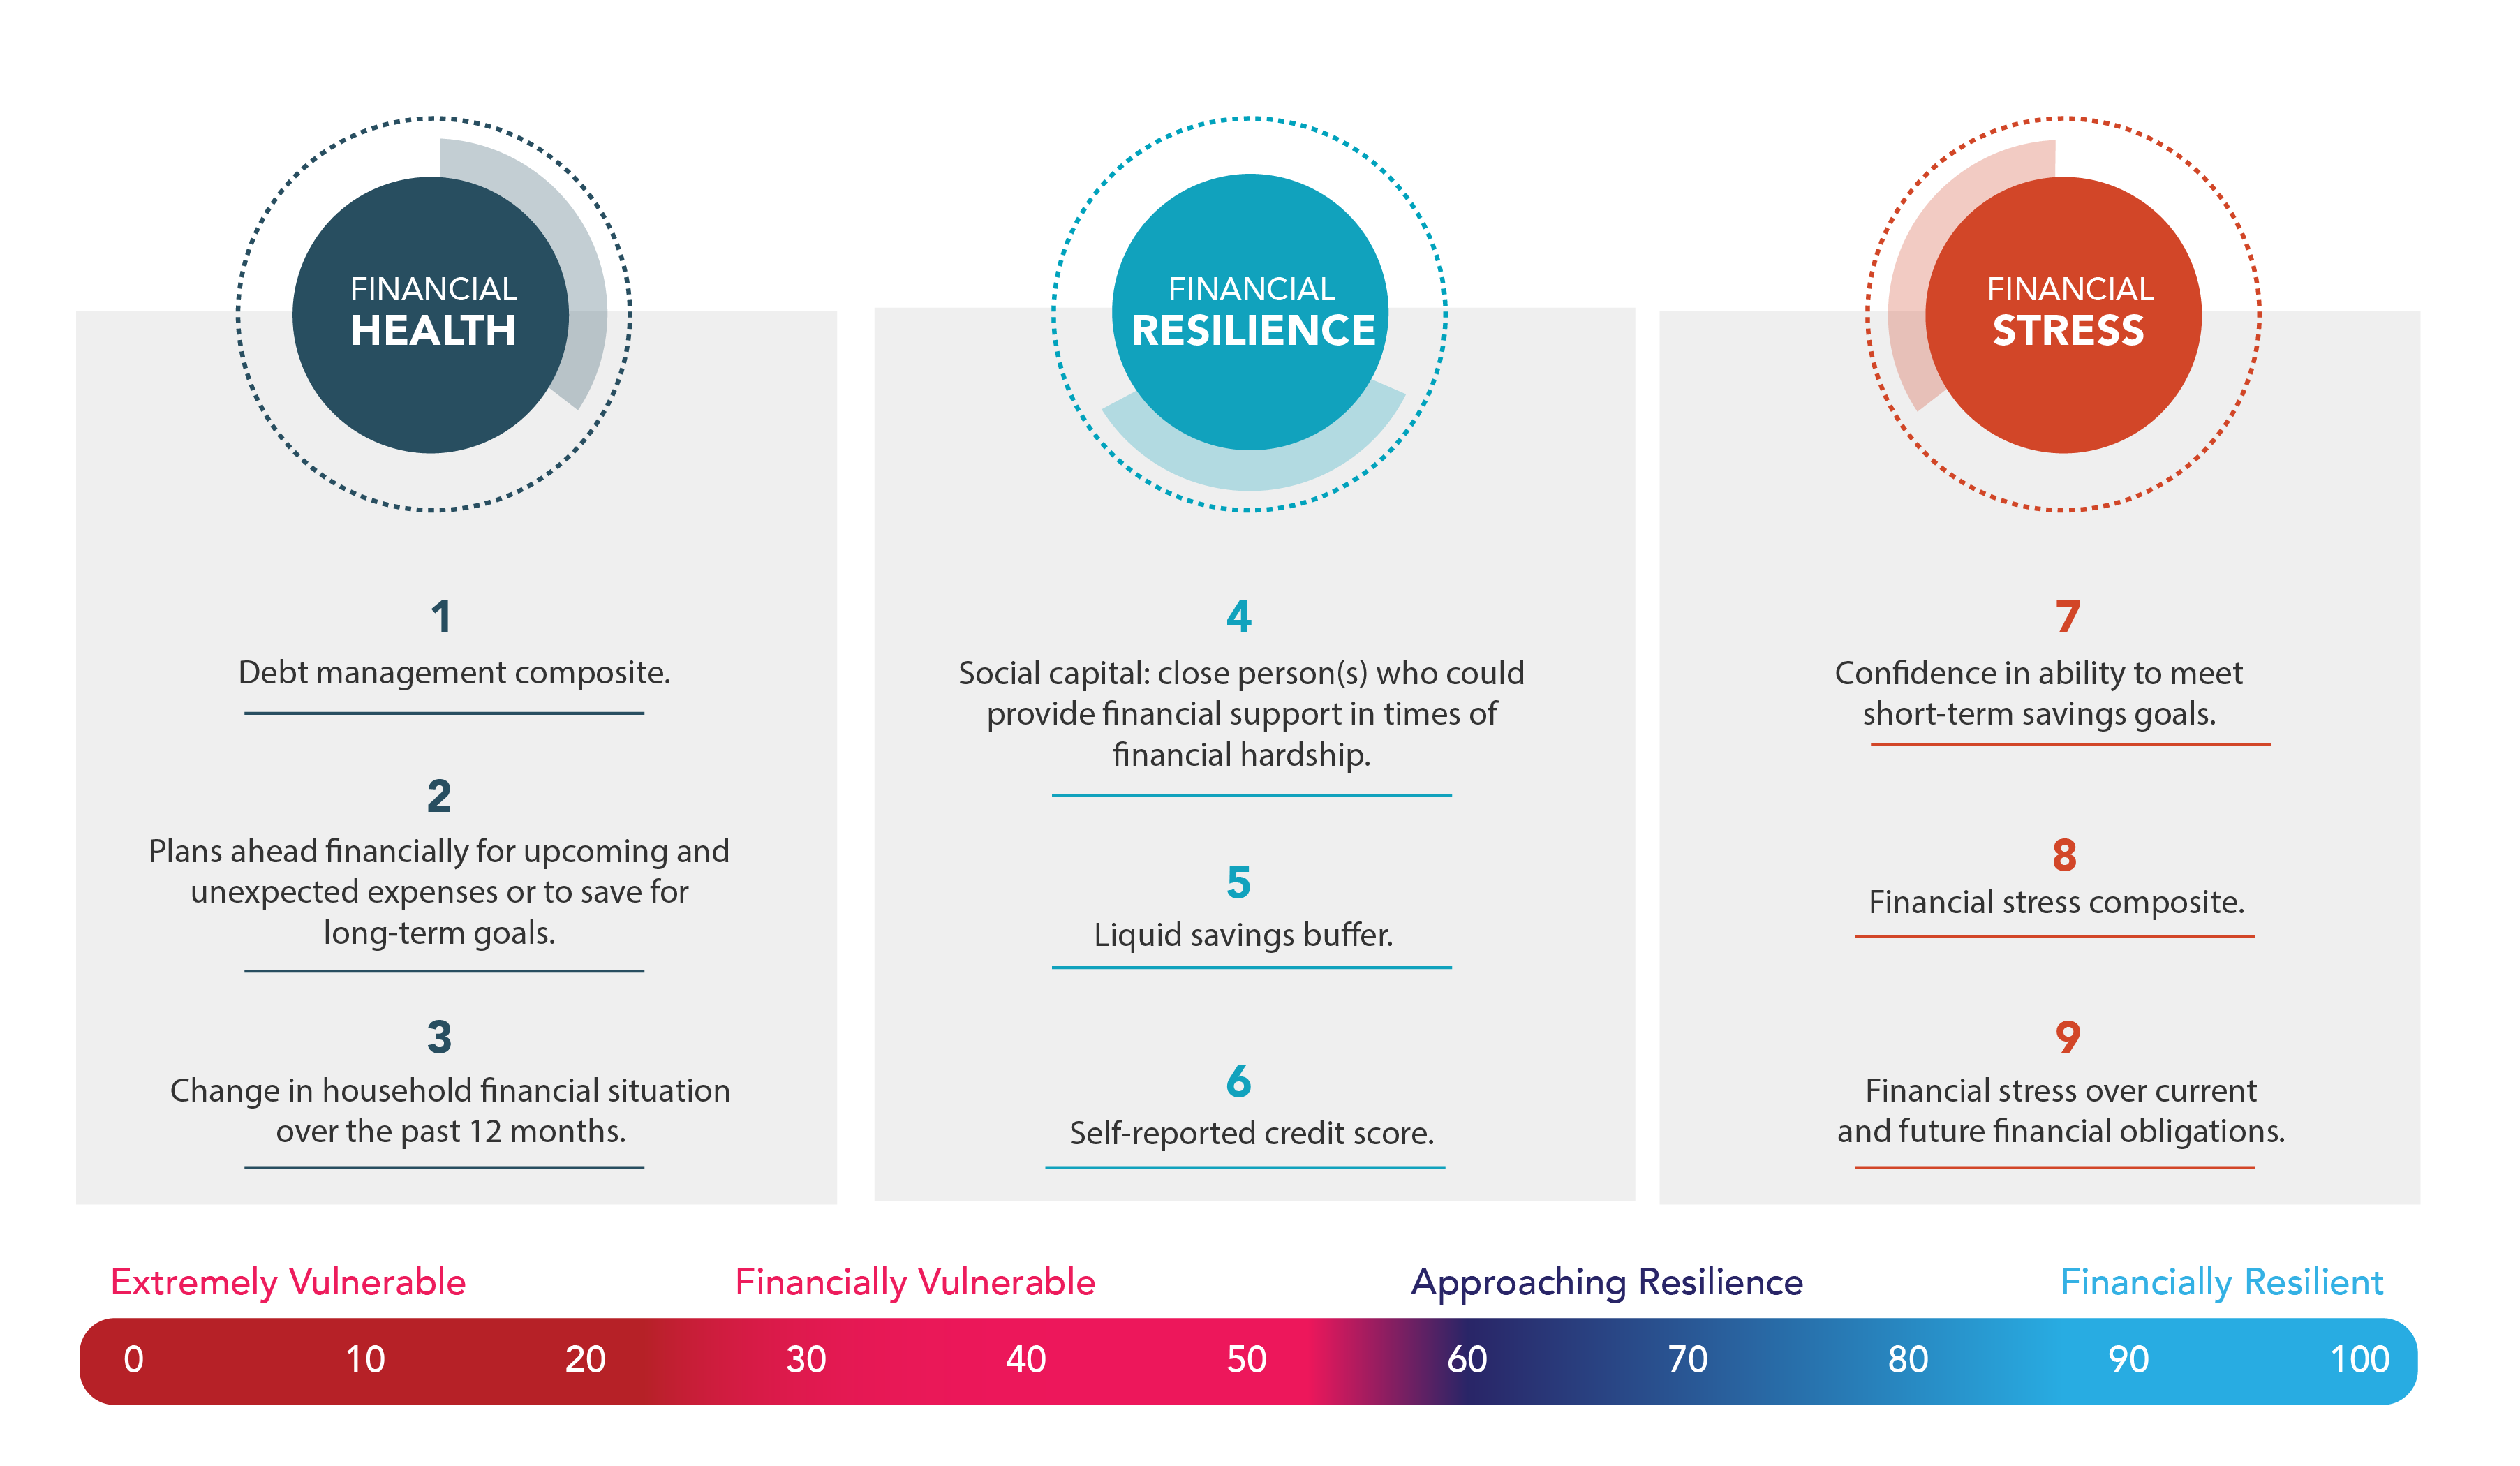
The Core Pillar: What Financial Resilience Truly Means
In conventional finance, resilience is often treated as simple risk aversion—holding excess cash, avoiding debt, and settling for conservative yields. Robertson approached the concept from an entirely different angle: resilience is not merely about defense; it is about building systems that thrive amid disruption.
To withstand volatile macroeconomic shifts, Robertson structured his financial life around three defensive guardrails:
- Liquidity Buffers: Maintaining a rolling 12-month operational reserve to ensure that forced liquidation of prime assets never occurred during market troughs.
- Non-Recourse Leverage: Utilizing debt conservatively and structuring liabilities so that operational challenges in one venture could not contaminate the broader portfolio.
- Uncorrelated Cash Flow: Diversifying revenue streams across business-to-business services, real estate, and equity investments to insulate cash flow from single-sector downturns.
By establishing these safeguards early, Robertson earned the freedom to take calculated, high-upside risks that more vulnerable competitors could not afford to take.
Jeb Robertson’s Financial Resilience – $60 Million Achieved in Less Than a Decade!
Generating $60 million in less than ten years requires compounding at an aggressive yet controlled rate. Robertson achieved this milestone not through a single high-profile exit, but through three structured phases of expansion.
Phase 1: Establishing the Cash-Generating Engine (Years 1–3)
Robertson began by building a high-margin enterprise focused on specialized commercial services. Instead of distributing profits to support lifestyle inflation, more than 85% of net revenues were retained and channeled into high-yield operating accounts and short-term capital investments.
During this period, Robertson focused intensely on operational efficiency. By automating fulfillment workflows, outsourcing non-core administrative functions, and keeping overhead exceptionally lean, the core business reached seven-figure annual profits within 36 months, providing the primary capital engine required for broader expansion.
Phase 2: Asymmetric Expansion and Real Asset Accumulation (Years 4–7)
With consistent operating cash flow secured, Robertson shifted attention to real estate and asset acquisitions. Instead of pursuing turnkey residential assets with compressed yields, he targeted value-add industrial real estate and secondary-market distribution hubs.
This phase was defined by opportunistic acquisitions during local market retractions:
- Acquiring Distressed Light-Industrial Properties: Purchasing undervalued parcels, modernizing logistics infrastructure, and securing long-term leases with regional logistics firms.
- Syndicated Equity Deployments: Partnering with vetted institutional operators to participate in class-B multifamily developments undergoing active repositioning.
- Reinvestment of Depreciation: Using cost segregation studies and capital expensing to minimize federal tax liabilities, legally redirecting seven figures in deferred tax savings directly back into cash-flowing assets.
Phase 3: Private Equity and Strategic Scaling (Years 8–10)

The final acceleration toward the $60 million mark occurred when Robertson transitioned from acquiring physical assets to acquiring operating equity in complementary niche businesses. By rolling up complementary service providers, his holding structure eliminated administrative redundancies, improved purchasing margins, and raised enterprise valuations.
When these businesses were recapitalized and institutional debt was retired, the net equity across Robertson’s consolidated portfolio surpassed $60 million—culminating a ten-year cycle of compounding, re-investment, and aggressive risk containment.
Key Wealth-Building Principles from the Robertson Model
While Robertson operated within specific business and real estate sectors, the principles underpinning his financial trajectory apply universally to modern capital allocators.
1. Prioritize Equity Value Over W-2 or Earned Income
High earned income is severely penalized by marginal income tax brackets and stops compounding the moment active labor ceases. Robertson recognized early that long-term net worth is built on balance sheets, not profit-and-loss statements. Every dollar generated by active effort was converted into appreciating equity, intellectual property, or tangible real estate.
2. Master the Asymmetric Bet
Robertson famously avoided balanced 50/50 bets, even when the potential payout was high. Instead, he sought asymmetric opportunities where the downside was strictly capped—such as properties with existing below-market leases—while the upside remained open-ended. If a thesis failed, the financial buffer absorbed the hit; if it succeeded, the returns elevated the entire balance sheet.
3. Emotional Detachment from Market Cycles
One of Robertson’s greatest competitive advantages was emotional neutrality. When commercial valuations soared and market participants adopted aggressive leverage, Robertson hoarded dry powder and secured refinancing. When credit markets tightened and competitors faced liquidity squeezes, he deployed accumulated cash to acquire premium assets at deep discounts.
Actionable Takeaways for Modern Investors
Applying the lessons of Robertson's ten-year journey does not require multi-million-dollar starting capital. It requires shifting operational priorities:
- Measure Your Personal Reinvestment Rate: Track the exact percentage of monthly net income that is allocated directly to wealth-generating assets versus lifestyle consumption.
- Build Redundancy Before Growth: Secure your baseline operating expenses with uncorrelated passive income or reserves before scaling risk exposure.
- Target Value-Add Opportunities: Avoid passive speculation; seek investments where your expertise, management improvements, or operational capital can directly force equity appreciation.
The Lasting Impact of Financial Resilience
Scaling a balance sheet from modest levels to $60 million in under a decade is an extraordinary outcome, but the true lesson lies in the architecture that made it possible. Jeb Robertson demonstrated that financial resilience is not a passive shield—it is an active vehicle for opportunistic compounding.
By safeguarding against catastrophic risk, reinvesting core cash flows with relentless discipline, and scaling assets with patience and precision, Robertson proved that financial independence is built through execution, process, and unwavering resolve.