Robins Federal Credit Union Personal Loan Rates Guide
When you need to finance a major purchase, consolidate high-interest debt, or cover an unexpected expense, finding the right lender matters. If you live, work, worship, or attend school in central Georgia, you might be eligible to join one of the region's largest financial cooperatives. Before applying, it helps to understand how robins federal credit union personal loan rates compare to traditional banks and online lenders.
Credit unions are known for returning profits to their members in the form of lower loan rates and higher savings yields. In this guide, we will break down what you need to know about Robins Federal Credit Union (RFCU), how their borrowing costs stack up, and what it takes to qualify.
Overview of Robins Federal Credit Union Personal Loans
Robins Federal Credit Union offers unsecured personal loans designed to give members flexible financing without needing to put up collateral like a home or a car. Because these loans are unsecured, your interest rate and borrowing limit depend heavily on your credit score, income, and overall financial history.
Unlike commercial banks that must generate profits for outside shareholders, RFCU operates as a not-for-profit financial institution. This cooperative structure typically allows them to pass savings along to borrowers through competitive Annual Percentage Rates (APRs) and fewer hidden fees.
Key Features of RFCU Personal Loans
- Fixed Interest Rates: Your rate remains locked in for the life of the loan, ensuring predictable monthly payments.
- No Prepayment Penalties: You can pay off your loan ahead of schedule without incurring extra fees.
- Flexible Terms: Repayment periods vary depending on the loan amount and your specific financial needs.
- Local Decision-Making: Applications are often reviewed locally, which can streamline the approval process.
Understanding Robins Federal Credit Union Personal Loan Rates
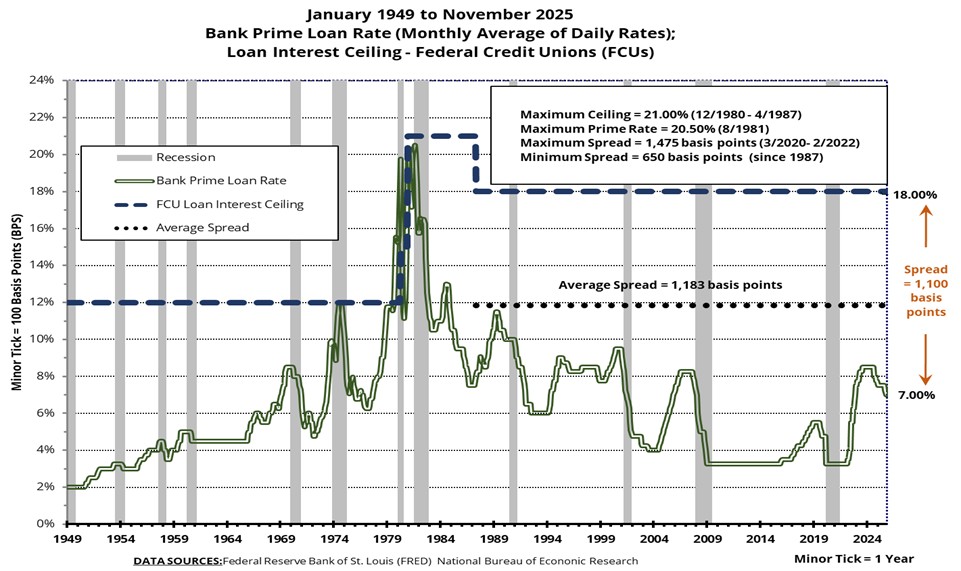
Interest rates change over time based on macroeconomic factors, including benchmark rates set by the Federal Reserve. While Robins Federal Credit Union does not always publish a single fixed rate publicly—often citing rates as "as low as"—their personal loan rates generally favor well-qualified borrowers.
Factors That Influence Your Rate
Your individual credit profile dictates the exact APR you will receive. Lenders evaluate several metrics when reviewing an application:
- Credit Score: Borrowers with excellent credit (typically 740 and above) secure the lowest advertised rates. Those with fair or developing credit may still qualify, but at higher interest rates.
- Debt-to-Income (DTI) Ratio: Lenders look at how much of your monthly income goes toward existing debt payments. A lower DTI ratio signals financial stability.
- Loan Amount and Term: Borrowing larger sums or choosing longer repayment terms can sometimes influence the interest rate you are offered.
Comparing Credit Union Rates to Traditional Banks
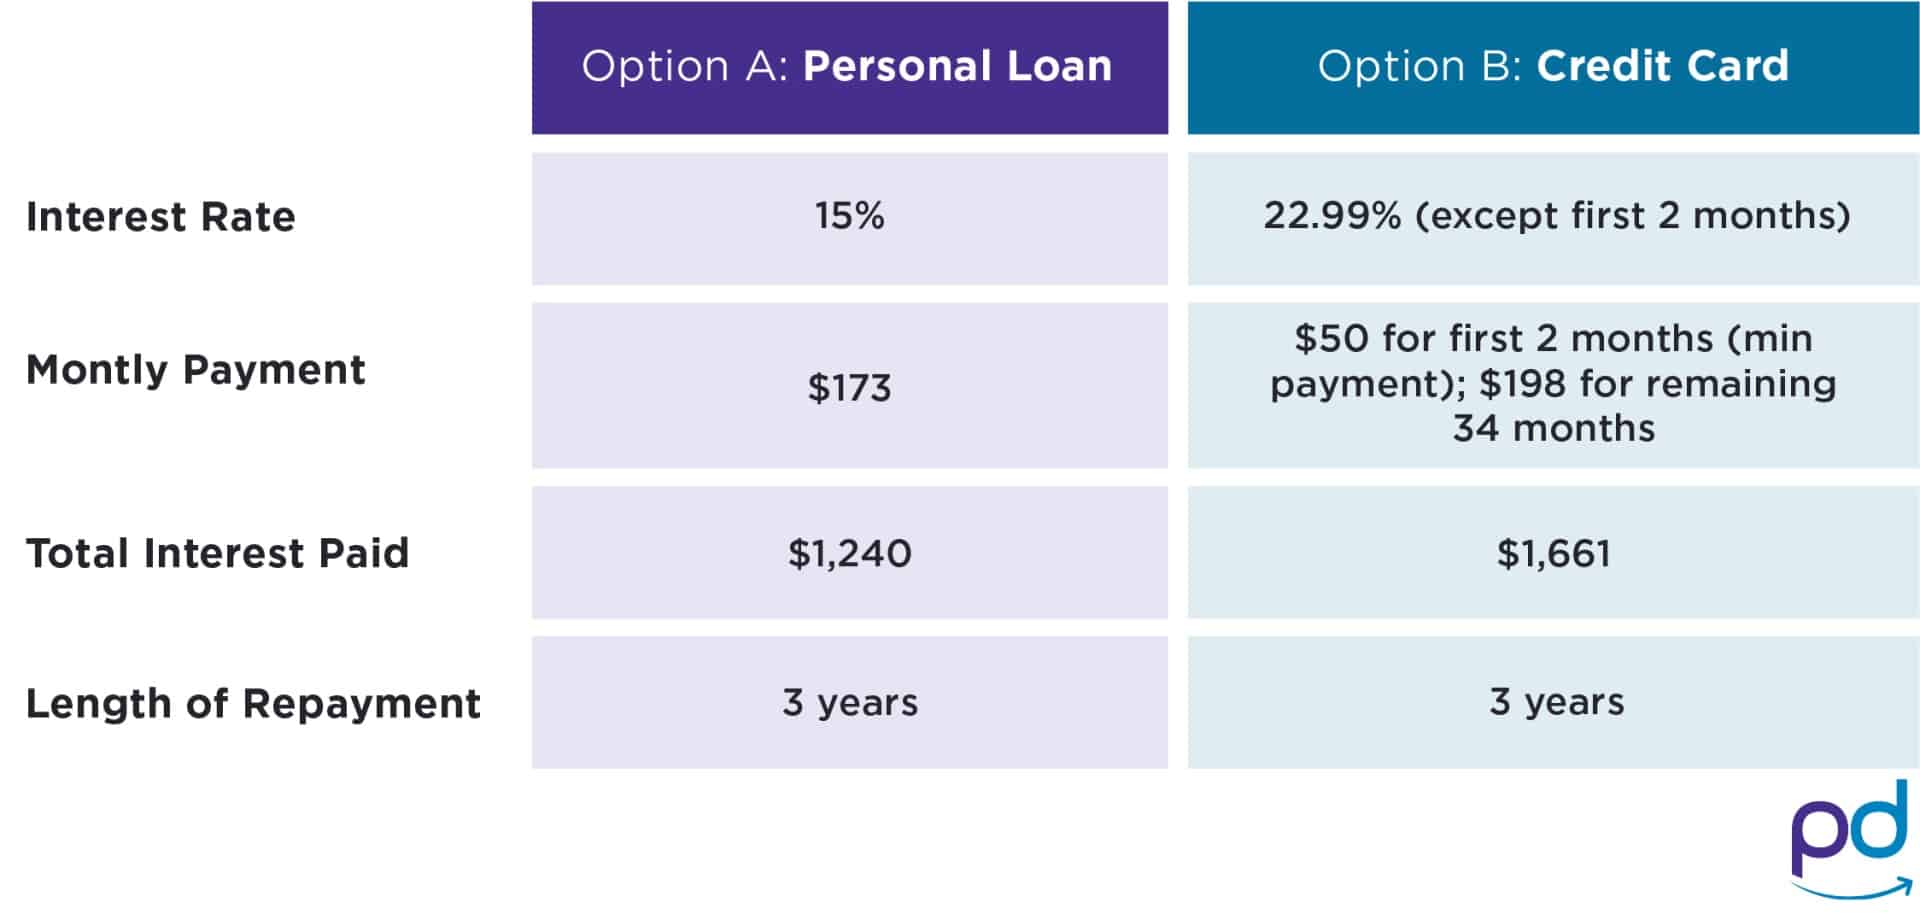
Historically, credit union personal loan rates tend to beat traditional commercial banks by 1% to 3% on average. For a multi-thousand-dollar loan, this difference can save you hundreds—or even thousands—of dollars in total interest charges over the life of the loan.
How to Qualify for an RFCU Personal Loan
Video: Understanding Your Home Loan: Robins Financial Credit Union
To access Robins Federal Credit Union personal loan rates, you must first become a member of the credit union. Membership is open to individuals who share a "common bond" tied to their geographic location or employment.
Membership Eligibility Requirements
You are typically eligible to join Robins Federal Credit Union if you:
- Live, work, worship, or attend school in select counties throughout central Georgia (such as Houston, Bibb, Peach, and surrounding areas).
- Are an employee, retiree, or family member associated with Robins Air Force Base or select partner companies.
- Open a share savings account with a small initial deposit to establish your membership.
Application Checklist
When you are ready to apply for a personal loan, gathering the right documents beforehand can speed up approval. Be prepared to provide:
- Proof of identity (government-issued driver’s license or passport).
- Proof of income (recent pay stubs, tax returns, or W-2s).
- Information regarding existing debts if you are applying for a debt consolidation loan.
Pros and Cons of Borrowing with Robins Federal Credit Union
Before signing a promissory note, weighing the advantages and potential drawbacks helps ensure you make the right choice for your wallet.
The Pros
- Competitive APRs: Often lower than major national banks and online installment lenders.
- Member-focused customer service and community involvement.
- No hidden fees or penalties for early payoff.
The Cons
- Geographic Restrictions: You must meet the field of membership requirements to join and borrow.
- Credit Score Dependent: To get the absolute best rates, you need a strong credit history.
Alternatives to Consider
If you do not live in Robins Federal Credit Union’s service area or want to shop around for the best deal, it is always smart to compare multiple offers. Consider checking rates with:
- Other large Georgia credit unions with broad field-of-membership rules.
- Online peer-to-peer lenders that specialize in fast digital funding.
- National banks where you already hold a checking or savings account.
Final Verdict
For residents of central Georgia who qualify for membership, exploring robins federal credit union personal loan rates is a smart financial move. Their commitment to member value, combined with competitive fixed rates and zero prepayment penalties, makes them a strong alternative to high-cost personal loans and credit cards. Take time to check your credit score, review your budget, and contact an RFCU loan officer to discuss your specific borrowing options today.