Your 401k’s True Net Worth Impact Is Far Bigger
When you log into your retirement account and look at the balance, you probably feel a mix of pride and anxiety. You see a raw dollar amount—say, $250,000—and mentally add that figure to your home equity and checking account to calculate your net worth. But financial planners know a secret: Your 401k’s true net worth impact is far bigger than you think — here’s why!
Traditional net worth calculators treat every dollar equally. They assume a dollar in a checking account has the exact same financial utility and future value as a dollar locked inside a tax-deferred retirement account. In reality, a 401k is a financial chameleon. It behaves less like a pile of cash and more like a leveraged, subsidized engine of wealth generation. Understanding the hidden layers of your 401k will completely change how you view your financial independence timeline.
The Illusion of the Nominal Balance
The most common mistake people make is looking at their 401k balance as a static pile of money. If your statement says you have $500,000, your brain registers $500,000. However, that number is misleading in two major directions: downward due to future taxes, and upward due to tax shelters and employer leverage.
To truly grasp your net worth, you have to look past the nominal balance and evaluate the structural advantages baked into the account. Let us break down the mechanics that make your retirement account punch way above its weight class.
1. The Tax-Sheltered Compounding Effect
Imagine you invest $10,000 in a taxable brokerage account versus a traditional 401k. In the taxable account, any dividends you receive are taxed annually, and if you reallocate your portfolio, you trigger capital gains taxes. The IRS takes a slice of your growth every single year, slowing your momentum.
Inside a 401k, that friction disappears entirely. Your dividends, interest, and capital gains compound in a vacuum.
- No annual drag: 100% of your earnings stay invested and go on to generate their own returns.
- Exponential divergence: Over a 20- or 30-year horizon, this lack of tax drag creates a massive chasm between a taxable account and a 401k holding the exact same investments.
This means the future purchasing power generated by a 401k dollar is fundamentally superior to a dollar grown in the open market, skewing your true long-term net worth trajectory upward.
2. The Employer Match Is Instant Arbitrage
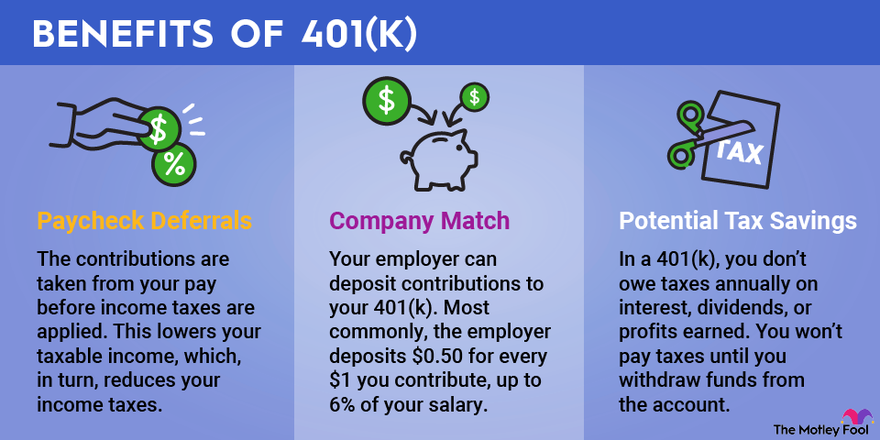
If your employer offers a match, your 401k delivers a guaranteed return that no stock market index can touch. A common structure is a 100% match on the first 3% to 5% of your salary that you contribute.
If you contribute 5% and get a 5% match, you have instantly doubled your money the second the trade executes. A 100% immediate return is an asset multiplier unlike anything else in personal finance. When calculating net worth, that match isn't just income; it’s an immediate, high-yield asset injection that lowers your personal capital risk while supercharging your portfolio base.
3. Asset Protection Fortresses

Net worth is not just about how much you accumulate; it is also about what you get to keep. This is where 401ks hold a massive, underappreciated advantage over other forms of wealth.
Under federal law (specifically ERISA), employer-sponsored retirement plans like 401ks receive extraordinary protection from creditors and lawsuits. If you face a catastrophic lawsuit, bankruptcy, or severe financial liability, the cash in your personal savings account or taxable brokerage might be vulnerable. Your 401k, however, is generally shielded entirely from ordinary creditors.
This means your 401k is a risk-free vault. Securing a portion of your net worth away from legal liability preserves your baseline security, making that wealth qualitatively superior to standard liquid assets.
The Hidden Catch: The Tax Liability Trap
We cannot discuss the true impact of a traditional 401k without addressing the elephant in the room: taxes. That $500,000 balance is not entirely yours. Every withdrawal you make in retirement will be taxed as ordinary income.
Calculating Your True Liquid Net Worth
To find the real net worth value of a traditional 401k, you must discount it by your expected future marginal tax rate. If you live in a high-tax state and expect to pull that money out in a high tax bracket, Uncle Sam might claim 25% to 35% of it.
However, even after discounting for future taxes, the tax-deferred nature of the contributions often works out in your favor. You typically contribute during your peak earning years when your tax bracket is highest, and withdraw during retirement when your income—and therefore your tax bracket—drops.
How to Leverage Your 401k for Maximum Wealth
Knowing that your 401k impacts your net worth more profoundly than basic math suggests should change how you manage it. Consider these optimization strategies:
- Never leave the match on the table: Walking away from an employer match is walking away from free net worth acceleration.
- Optimize your asset location: Put high-growth, tax-inefficient assets (like actively managed bond funds or REITs) inside your 401k, where their tax burdens won't hurt your growth.
- Plan for Roth conversions: If you expect your future tax bracket to be higher, or if you want to mitigate Required Minimum Distributions (RMDs), strategically converting traditional 401k funds to a Roth 401k or IRA can optimize your long-term net worth retention.
Conclusion
Your 401k is much more than a retirement piggy bank. Through tax-free compounding, risk-free legal protections, and immediate employer matches, it functions as a foundational pillar of your lifelong financial architecture. Look past the simple arithmetic on your annual statement, optimize your contributions, and start treating your retirement account for the powerful net worth multiplier that it truly is.